





Add-on acquisitions made up 74.1% of US private equity buyouts by deal count in Q32025, PitchBook reports, and the add-on is the basic unit of a roll-up. A roll-up strategy is an acquisition strategy in which one buyer, usually a private equity platform or a strategic acquirer, buys and integrates many small companies in the same fragmented industry to build one business worth more than the sum of its parts. Waste Management, Service Corporation International and IVC Evidensia were built this way. In more than a decade as an M&A advisor, and since founding DealRoom in 2012, I have seen roll-ups succeed on integration and fail on overpaying.
What is a roll-up strategy?
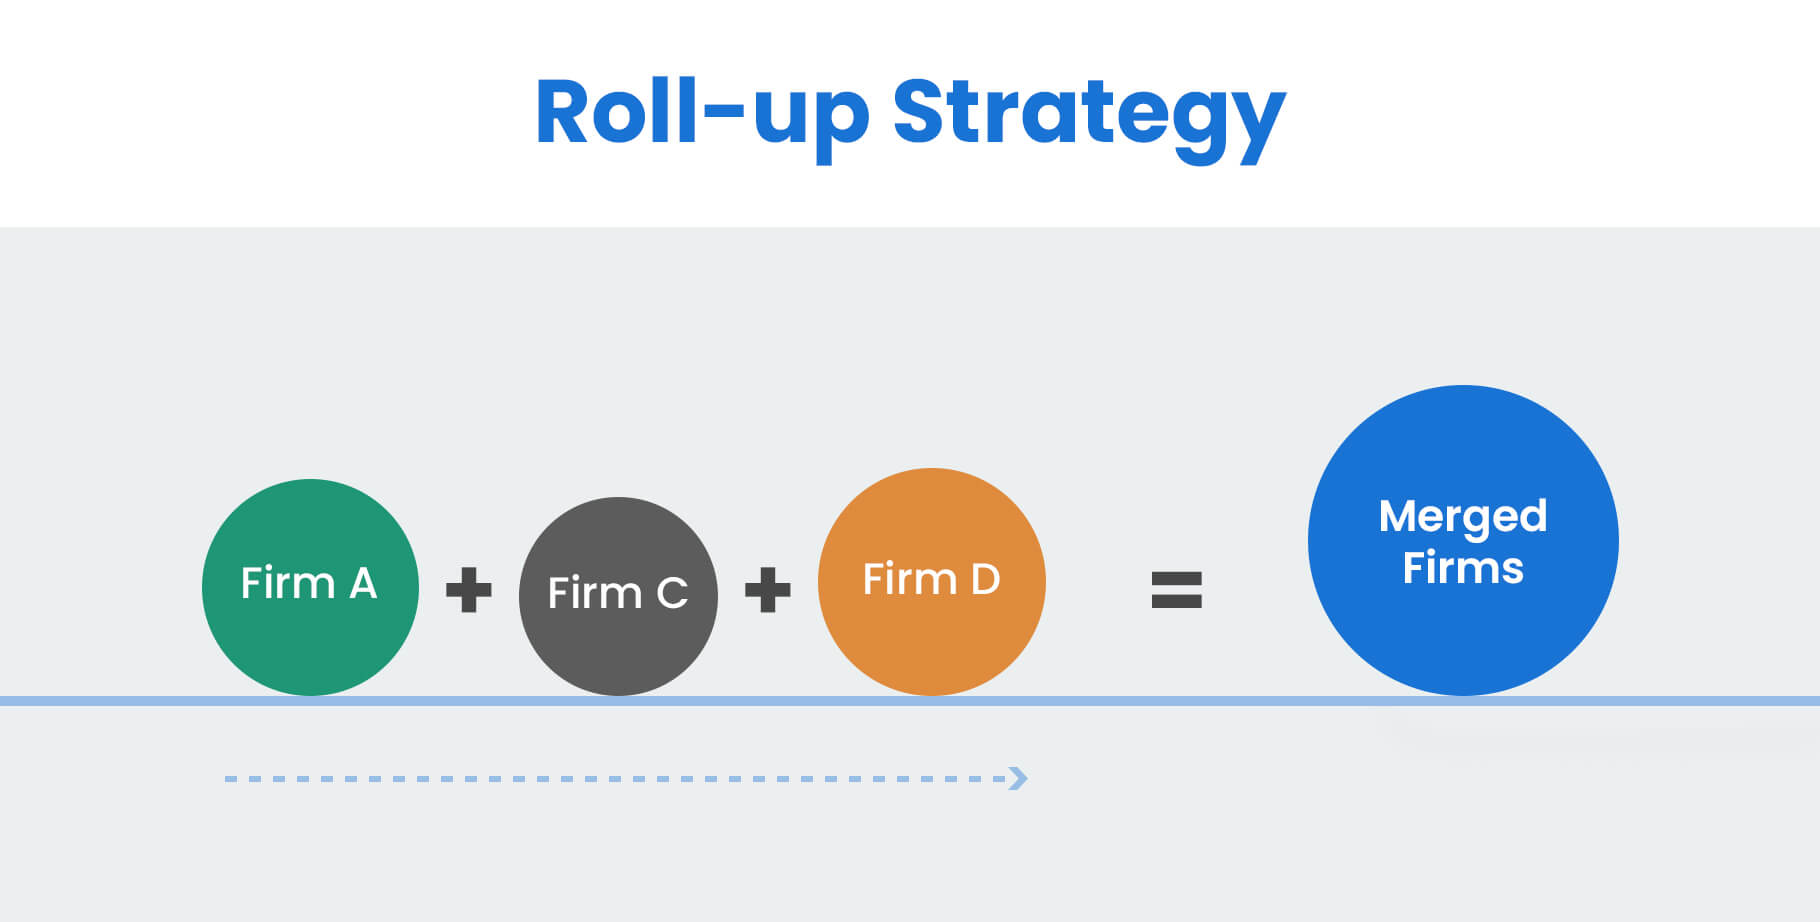
A roll-up strategy is a focused acquisition strategy that involves the acquisition of multiple smaller companies (sometimes referred to as ‘bolt-on acquisitions’).
The roll-up strategy tends to be more common in industries that are fragmented, but it can happen anywhere that these bolt-on acquisition opportunities present themselves.
The end goal of a roll-up strategy is a company of much larger value that is more than the sum of its parts.
A study conducted by McKinsey over the course of two decades into successful M&A will disappoint followers of megadeals.
Pursuing a series of smaller deals, the total value of which is relatively close to the acquiring company’s market capitalization, rather than focusing on eye-catching ‘big bang’ transactions, tends to generate far more value.
In short, the research advocated a roll-up strategy for companies considering M&A. McKinsey's latest update found that programmatic acquirers earned a median excess total shareholder return of 2.3% a year over the decade to 2022, ahead of every other M&A approach and of organic growth.
Above all, we show how, in some industries, the leaders have gained their winning position through successfully executing roll-up strategies rather than being so-called disruptors.
So while McKinsey’s research refers to an M&A roll-up strategy as ‘programmatic M&A’, a far more accurate term may be ‘pragmatic M&A’.
Why do investors love roll-ups?
The roll-up strategy model is attractive to investors for its value-generating potential. This value is achieved in a number of ways:
- Economies of scale: The entity created from the roll-up strategy should enjoy economies of scale (e.g., increased buying power) well beyond any of the smaller companies that it is composed of.
- Benefits of synergies: A well-executed roll-up strategy should benefit from a range of synergies that generate value at the margins. For example, shared administration and marketing costs.
- Increased exposure: As a larger entity, the entity created from the roll-up strategy will have increased exposure, giving it access to a larger audience and making it the focus of increased media attention.
- Access to better opportunities (including capital): Bigger companies, as a rule, tend to enjoy a liquidity premium that lowers their cost of capital and allows them to access opportunities (e.g., more acquisitions) than smaller companies can.
How roll-ups create value: multiple arbitrage,platforms and add-ons
Roll-ups make money in three ways: multiple arbitrage, synergies and growth the acquired companies could not fund alone. Multiple arbitrage is the one specific to roll-ups. Small, owner-operated businesses sell for low multiples of EBITDA because few institutional buyers will look at them. A scaled platform with audited financials, professional management and diversified revenue sells for a higher multiple. Buy at the low multiple, exit at the high one and the spread is return before any operating improvement.
An illustrative example (DealRoom's own assumptions, not market data): a sponsor buys a platform with $10 million of EBITDA at 8x, or $80 million, then adds ten companies with $1 million of EBITDA each at 5x, or $50 million in cost is $130 million for $20 million of EBITDA, a blended 6.5x. If the whole business exits at 10x, enterprise value is $200 million and $70 million of value was created. About $50 million of that comes from re-rating the add-on earnings from 5x to 10x.
The structure behind the math is the platform and add-on model.
The platform is bought first and at full price because it supplies the management team, reporting and systems every later deal plugs into. Add-ons are bought cheaper and faster. PitchBook counted add-ons as 74.1% of all US private equity buyouts by volume in Q32025, against a five-year average of 72%. The arbitrage only holds if add-ons are integrated well enough that the next buyer pays the platform multiple for their earnings. A loose group of small shops under one earns no premium.
Roll-up vs buy-and-build: what the difference is
A roll-up and a buy-and-build use the same tool kit, and the two terms are often swapped, but they describe different starting points. A roll-up is any consolidation of many small companies in one fragmented industry into a single larger business, whoever is doing the buying: a private equity sponsor, a founder-led consolidator, a listed strategic or a holding company. Buy-and-build is the private equity version. Bain defines it as a strategy built around "a well-positioned platform company" that then makes at least four sequential add-on acquisitions, and it excludes companies that make one or two opportunistic add-ons.
Three things separate them in practice. Sequence: a buy-and-build always buys the platform first, at full price, and adds on over the hold period, while a roll-up can buy several similar-sized targets at once, sometimes at the same closing. Pace: a buy-and-build integrates each add-on before the next, usually across a three to seven year hold, while roll-ups tend to be front-loaded. Source of return: a roll-up leans on multiple arbitrage and scale, so pricing discipline on each deal matters most, while Bain found the buy-and-build winners pull four lever sat once, arbitrage, synergies, operating improvement and growth.
The add-on is now the default private equity deal. PitchBook counted add-ons as 74.1% of US buyouts by deal count in Q3 2025, and Preqin reported that add-ons made up more than half of global private equity deal count in the first half of 2026. Bain found that around 30% of add-on transactions are the platform's fourth or later acquisition, which is the point where it calls the program a buy-and-build. In FTI Consulting's 2026 survey of more than 550 private equity leaders, 24% ranked M&A as their top value generator, up from 7% a year earlier.
A simple test for which one you are running: if the first deal is larger than the rest, carries the management team and systems, and every later deal is priced against its multiple, it is a buy-and-build. If you are assembling several businesses of similar size at the same time and the case rests on the combined company earning a higher multiple than its parts, it is a roll-up in the narrower sense, and the discipline that matters is the price paid on each deal rather than the order of integration.
Importance of having a disciplined roll-up strategy
A roll-up strategy doesn’t generate value on its own.
As DealRoom is constantly at pains to emphasize, acquisitions are complex projects that require diligent project management.
This means excellent planning, ensuring cultural and operational fit, thorough due diligence, and sound deal structure for each acquisition.
By extension, when there are many acquisitions, this workload should increase. Just because the companies are smaller, it doesn’t mean that you can take shortcuts in the process.
Best practices for successful roll-up strategies
The nature of an acquisition roll-up strategy is that most strategies are implemented over a period of three to four years.
Here is what can be found amongst best practices:
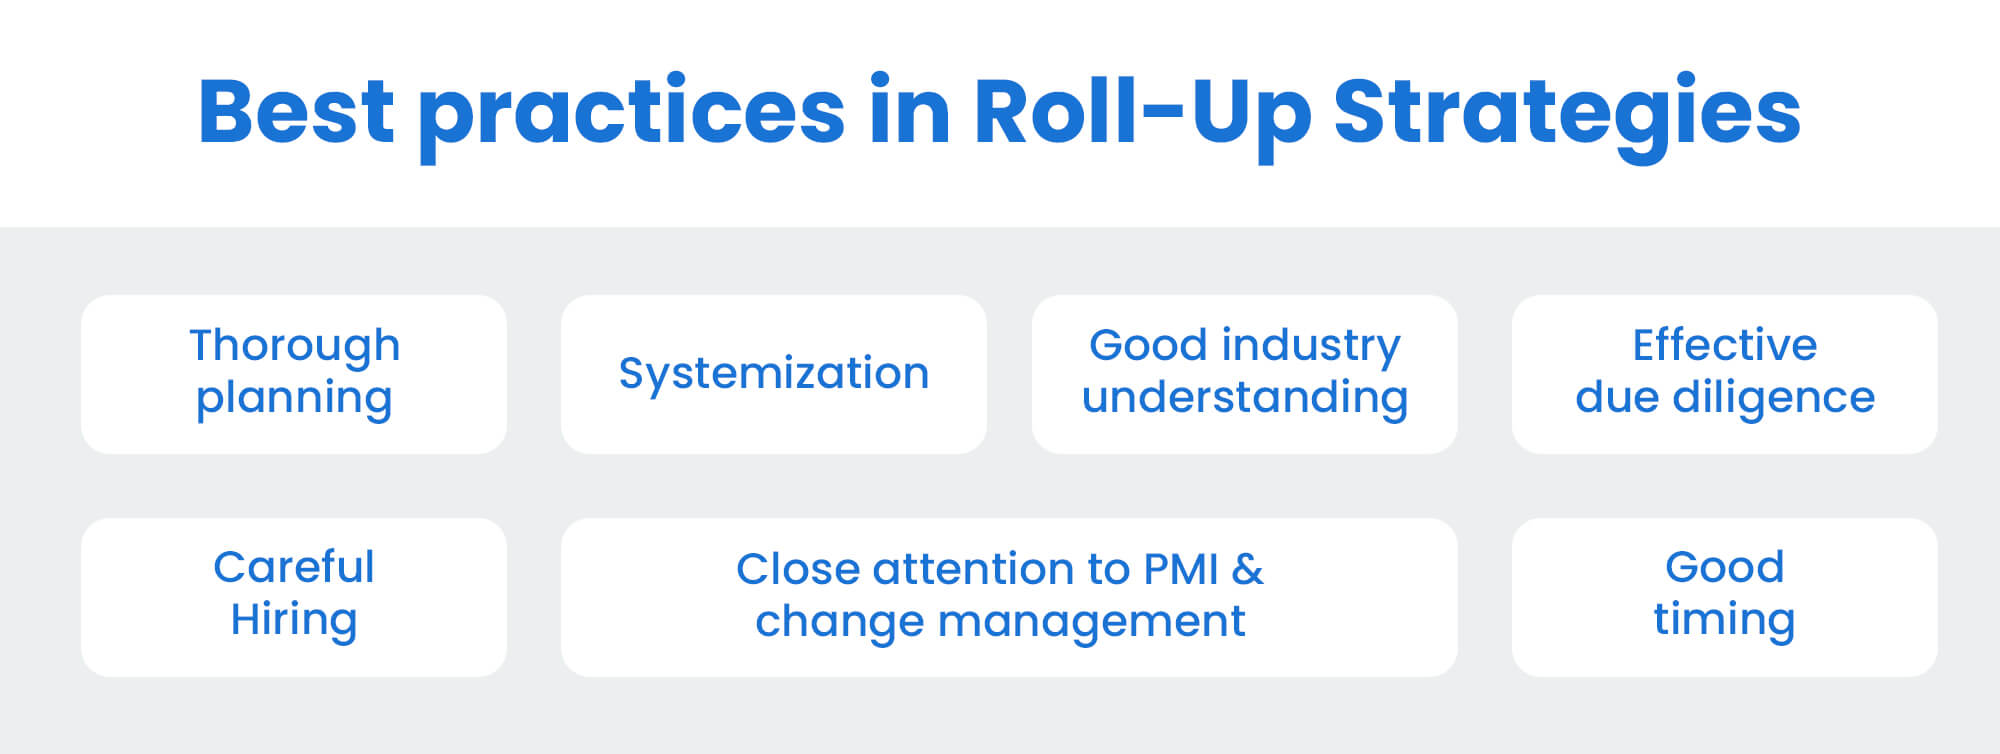
Generally, the more strategically and diligently your business approaches a roll-up, the greater the likelihood of a successful outcome.
That said...
Here is a detailed overview of key steps to start with when you're considering roll-up as a strategy for acquisition:
- Planning: Lots of it. Nobody should consider a roll-up strategy without planning five years ahead. At this stage, the team should be considering the maximum multiple of EBITDA that will be paid for the acquisitions, the geographies that the company is interested in, and the level of equity that it is willing to hand over to each of the acquired companies’ owners.
- Develop systems: This should be part of the planning process, but it deserves a mention of its own. It should go without saying that a mid-sized corporation needs more systems to operate successfully than would a small, local company. For example, if the manager of a recently acquired company were to abruptly up sticks and leave, how easily would the business be run in his absence? Systemization is required to ensure zero disruption in cases like this.
- Understanding the industry: Some industries benefit from scale more than others. Likewise, certain industries aren’t fragmented enough to warrant implementing an acquisition roll-up strategy. Sluggish industry growth or less-than-optimistic future prospects are also important to understand. It’s crucially important to understand the industry, its dynamics, and its future prospects.
- Due diligence: More acquisitions mean more due diligence. As a result, for any company implementing an acquisition roll-up strategy, due diligence effectively becomes a core part of the company’s operations—not unlike its finance or HR department. And as due diligence becomes bigger, the acquiring company will need to hire a bigger team to ensure that it’s being conducted with the same rigor for every single transaction.
- Careful hiring: Closely related to due diligence is the need for the team behind the roll-out strategy to ensure management competency. The bigger the company becomes, the more difficult it becomes to manage. Does the new entity require a level of middle management or regional managers? Who is responsible for overseeing the day-to-day management of its new branches?
- Integration: All the businesses need to be well integrated to ensure that the new entity is more than the sum of its parts. Without post-merger integration and change management, the acquirer risks being left with nothing but a group of disparate companies (and disgruntled managers and staff) on their hands.
- Timing: There is no universally ideal timing for executing a roll-up strategy. While moving quickly can offer advantages—such as preventing target companies from catching on and demanding higher EBITDA multiples—speed alone isn’t the key. A rushed approach risks overlooking critical elements like due diligence, proper valuations, and strategic alignment. The goal is to strike the right balance between speed and thoughtful execution.
Key metrics to track
It’s easy to lose focus in a roll-out investment strategy and to allow the acquisitions to become the goal in themselves rather than just the means to a much bigger end goal.
Putting in place a range of metrics (or KPIs) enables acquirers to keep their eyes on the prize.
The following are just some of those KPIs (with operational KPIs varying by industry):
- Ownership distribution
- Pre- and post-merger performance levels at each company
- Debt/equity levels at the holding company (and blended cost of debt)
- The average acquisition EBITDA multiple
- Time to close each acquisition
- Employee turnover levels
- Operational costs at the holding company (should be less than that of the combined firms)
How roll-ups are financed: debt, rollover equity andearnouts
How is a roll-up financed? The platform is bought with sponsor equity and senior debt. Each add-on is then paid for with debt drawn under the platform's credit facility, cash from the combined business, rollover equity from the selling founder, often an earnout and sometimes a seller note. The mix shifts toward paper as the targets get smaller.
Roll-up acquisitions are financed in two layers: sponsor equity and senior debt buy the platform, then rollover equity, earnouts and seller notes pay for much of each add-on. The platform is bought like any leveraged buyout. Sponsors contributed 46% equity on US buyouts in 2025, against a ten-year average of 41% through 2021, according to PitchBook LCD. Smaller platforms borrow from regional banks, private credit funds and SBIC lenders, and at the smallest end an SBA 7(a) loan covers a change of ownership up to $5 million. Lenders usually size a delayed-draw term loan or an accordion at close so later add-ons can be funded without a new credit agreement each time. The covenants are tested on the combined group, which is why one weak add-on can put the whole platform in default.
Add-ons are cheaper to finance because they are bought at lower multiples and partly paid in paper. Rollover equity in a private equity roll-up is the portion of the purchase price the selling founder reinvests into the platform's holding company, making the founder a minority owner of the larger business instead of taking all cash. In the SRS Acquiom 2026 M&A Deal Terms Study, 21% of 2025 private-target deals combined cash with a management rollover, up three points on the year. Buyers want it because it keeps the founder working for the exit and lowers the cash needed at close. Sellers can often defer tax on the rolled portion, especially when the company is an LLC, but the structure has to be set before signing. The terms a seller should check are the class of equity (the same units the fund holds, not a junior class), protection against dilution by later add-ons and what the drag-along rights oblige them todo at exit.
Earnouts bridge a price gap on founder businesses with uneven earnings. They appeared in24% of 2025 deals, with a median potential payout of 34%of the closing payment. In a roll-up they are harder to administer than in a standalone deal because the acquired company's P&L stops existing on its own once it is integrated, so the metric, the accounting basis and the treatment of shared costs have to be written down before close. Seller notes, subordinated to the bank, fill the rest of the gap on the smallest add-ons. Indemnity protection follows the same pattern as any private deal: the median escrow was 10% of deal value in 2025 and representations and warranties insurance appeared on about 46% of deals, though premiums rarely make sense on a small add-on, so escrows do the work there.
Across a dozen add-ons these instruments pile up: several rollover classes on one cap table, overlapping earnout periods and a credit agreement that each new deal has to fit inside. In my experience the roll-ups that keep their lender's confidence are the ones that can produce the debt schedule, the rollover cap table and every open earnout test on request, because that is the first thing asked for at the next add-on.
Why folding companies under one umbrella isn’t simple
In a word: integration.
Put simply, integrating five companies, each generating $5 million in revenue, is no easier than integrating a single company with $25 million in revenue.
Successful roll-ups require the acquirer to operate as a true integration specialist—skilled at unifying operations, systems, and cultures under one umbrella.
And of course, there are external market issues that the acquirer has no control over, which can wreck any roll-up investment strategy, even if the integration processes have gone smoothly.
How to find the right industry for roll-ups
In short, the best industry to implement a roll-up strategy is one where there is:
- No clear industry leader.
- Little industry consolidation.
- Returns to scale.
- Positive growth forecasts.
- Owners willing to sell.
As mentioned in the sections above, before implementing a roll-out investment strategy, it is important to understand an industry’s dynamics (nationally, if the roll-out strategy is national, and internationally, if it is international or global).
The most common proponents of roll-out strategies are private equity firms. These firms can spend up to two years at a time establishing which industries are suitable for roll-outs.
An example of private equity roll up strategy here is useful. Consider the dairy industry. Although most countries tend to have at least one dominant player, there will also be a number of smaller regional players making milk and selected dairy products for their local market.
Perhaps some will even have a limited export component. As a steady but usually not fast-growing industry,
Now, if someone were to begin acquiring these companies, they would be able to offer an extended range of products (milk, powdered milk, cheese, artisan cheeses, etc.) across a much wider geographic area.
There would also be benefits of scale—for example, better bargaining power with farmers and supermarkets. The fact that the brand was now nationwide means that it would gain stronger marketing power.
But also think of the value-adding potential of the deal. Perhaps some of the smaller dairy companies were only producing liquid milk.
What if the extra milk output could now be turned into higher-value products such as gorgonzola, camembert, or brie cheese by the new company?
Suddenly, the same inputs are generating 2x to 3x the value as before.
And you begin to see where a roll-up strategy can become so powerful when executed properly.
Examples of roll-up strategies for private equity firms
Private equity firms often pursue roll-up strategies in fragmented industries where consolidation can create operational efficiencies, increase market share, and boost valuation multiples. The add-on is now the default private equity deal: PitchBook reports that add-ons accounted for 74.1% of all US PE buyouts by volume in Q3 2025, against a five-year average of 72%. The examples below show how that activity is organized sector by sector.
Dental rollup strategy
The dental industry is a classic target for roll-ups due to its fragmentation, recurring revenue models, and resilience to economic downturns. Private equity firms acquire multiple small dental practices and centralize functions like billing, HR, and marketing under a dental support organization (DSO).
This organizational structure allows dentists to focus on clinical work while back-office operations are streamlined. The model is spreading fastest among younger dentists: the ADA Health Policy Institute found that more than 1 in 4 dentists within 10 years of dental school were affiliated with a DSO in 2024.
Economies of scale, improved supply chain leverage, and the ability to cross-sell specialty services across locations drive value creation.
HVAC rollup strategy
HVAC services (heating, ventilation, and air conditioning) are essential, highly localized, and often owner-operated. Private equity firms executing HVAC roll-ups focus on acquiring regional providers with strong reputations, then unifying them under a shared brand and support infrastructure.
These roll-ups aim to optimize routing and scheduling service technicians, cross-train technicians, and improve profit margins through shared procurement. Seasonal demand cycles and recurring service contracts make HVAC especially appealing for steady cash flow. PitchBook counted 55 private equity deals in HVAC in 2024, up 72% on 2023and the highest annual total since at least 2017.
Daycare rollup strategy
Childcare centers are another fragmented industry where roll-ups can generate significant value. PE firms acquire small, independent daycares and standardize curriculum, licensing, and compliance processes.
A key focus is enhancing parent experience through technology (e.g., mobile apps for daily updates), building trusted brands, and expanding after-school offerings. Roll-ups in this space benefit from increased demand due to dual-income households and ongoing demographic trends.
Veterinary rollup strategy
Veterinary clinics share many of the characteristics that make dental and daycare businesses attractive, including fragmentation, high client retention, and recession-resistant services. PE firms often establish veterinary practice management groups to oversee operations across multiple clinics. Consolidation is already well advanced: Brakke Consulting estimates that 25% of US general practices and 75% of specialty practices are corporately owned.
Consolidating procurement, implementing EMR systems, and scaling marketing enable firms to achieve significant margin improvement and a stronger negotiation position with suppliers.
Physical therapy rollup strategy
Physical therapy is another growth area for roll-ups, particularly as aging populations and sports injuries fuel demand. Private equity firms target clinics with strong local ties and skilled therapists, aiming to improve operational consistency and patient outcomes.
National networks of physical therapy clinics benefit from shared referral sources, payor contract negotiation, and telehealth integration.
Funeral services rollup strategy
Funeral homes remain highly fragmented and are often family-owned. PE firms consolidate these businesses to benefit from predictable revenue, real estate value, and pre-need contracts.
Roll-ups in this space focus on improving digital presence, centralizing customer service, and offering a wider range of memorial services under one brand.
Home healthcare rollup strategy
Home healthcare, which encompasses in-home nursing, physical therapy, and personal care, is experiencing rapid growth due to the aging population and a growing demand for aging-in-place solutions. PE-backed roll-ups in this sector focus on acquiring licensed providers and unifying care delivery standards, compliance frameworks, and EMR systems.
Centralized staffing platforms, payer relationship management, and telehealth integration help create more efficient, scalable operations. These roll-ups also benefit from Medicare and Medicaid funding and continued demand for chronic care management at home.
Landscaping rollup strategy
The landscaping industry is highly fragmented, with thousands of small operators serving local markets. Private equity firms pursuing landscaping roll-ups target companies with recurring maintenance contracts, strong regional brand presence, and a reliable workforce.
Consolidation efforts focus on standardizing service offerings (e.g., lawn care, irrigation, snow removal), investing in centralized scheduling and CRM tools, and creating purchasing leverage for equipment and materials. Integrating back-office functions and unifying marketing allows firms to build regional market leaders capable of serving residential and commercial clients at scale.
Auto repair rollup strategy
Auto repair shops are typically independent, owner-operated businesses that vary in quality and the range of services offered. PE firms pursuing roll-ups in this sector focus on acquiring reputable mechanics and rebranding them under a national or regional banner.
Consolidation enables better parts procurement, unified digital booking systems, technician training programs, and customer loyalty strategies. These roll-ups also benefit from increased consumer trust through brand consistency and can expand revenue by upselling services, fleet maintenance, and extended warranty work.
The table below breaks down the key aspects of private equity roll-up strategies across these industries.
Case studies of successful roll-up companies
Roll-up strategies have built some of the most dominant companies in waste services, auto retail, brewing, veterinary care, funeral services and pest control.
The examples below show how focused execution and integration create significant enterprise value.
Waste Management
Waste Management’s roll-up strategy is methodical and aggressive. Starting in the late 1970s and accelerating through the 1980s and 1990s, the company acquired hundreds of small, local waste haulers across North America.
These were often family-owned businesses with strong customer relationships but limited resources. Waste Management moved quickly to consolidate these fragmented operations under one national brand, locking in regional dominance before competitors could react.
Waste Management standardized equipment, billing systems, and safety protocols. It also centralized procurement to drive down costs and implemented uniform pricing structures to boost margins. This enabled the company to scale effectively enough to command favorable landfill access, invest in waste-to-energy technology, and secure long-term municipal contracts.
AutoNation
AutoNation’s roll-up strategy is focused on scale and standardization. In a fragmented market of family-run dealerships, AutoNation seized the opportunity to consolidate independently operated lots into a unified, publicly traded network with centralized branding, operations, and pricing controls.
Early on, AutoNation moved fast, acquiring dozens of dealerships in quick succession. It targeted high-performing locations in major metro areas and immediately brought them under a common operating system. The company centralized advertising, standardized inventory systems, and reshaped sales and service processes for consistency and efficiency.
By 1999, AutoNation was the largest car retailer in the U.S. While it has since been surpassed by Lithia Motors in 2022, AutoNation remains one of the largest US dealer groups. Lithia reported record 2025 revenue of $37.6 billion against AutoNation's $27.6 billion, and AutoNation added five stores with more than $650 million of annual revenue in 2025.
AB InBev
AB InBev built a beer empire by systematically acquiring major brewers and overhauling their operations to eliminate inefficiencies and boost profit margins. Its first major move was acquiring Anheuser-Busch for about $52 billion in 2008,which gave the company the leading share of the U.S. market. In 2016, AB InBev acquired SAB Miller in a deal valued at more than $100 billion, still the largest beer deal in history. The combined group reported revenue of $59.3 billion for 2025.
The strategy focuses on buying undervalued or under-optimized brewers with strong local brands. Following an acquisition, they eliminate redundant costs and centralize procurement, marketing, and back-office functions.
AB InBev embraced a zero-based budgeting model, meaning every cost must be justified from scratch each year. As a result, the company sidelined brands that didn’t drive volume or margin, enabling a stronger focus on the brands that delivered the most value.
IVC Evidensia
IVC Evidensia, a company with more than 2,500 locations spanning 20 countries, executes a high-volume, PE-backed roll-up strategy in the veterinary sector, acquiring up to 300 small, independent clinics annually (and as many as 56 in a single month) in 12 geographic regions. The strategy focuses on centralized due diligence, streamlined legal and integration workflows, seller-friendly onboarding, and operational standardization.
To overcome inefficiencies from fragmented data and cross-border complexity, IVC adopted DealRoom’s M&A platform. This enabled faster contract reviews (cutting time from 30 to 2 minutes), eliminated siloed tools, and improved multilingual seller communications.
IVC Evidensia’s success as a high-volume acquirer reflects the core principles of Buyer-Led M&A™, an approach designed to give acquirers more control, consistency, and speed across the deal lifecycle.
By centralizing diligence, standardizing processes, and adopting purpose-built technology like DealRoom, IVC shifted from a reactive, seller-led model to a proactive, buyer-driven approach, enabling the company to scale rapidly while maintaining deal quality and execution speed.
Service Corporation International
Service Corporation International (SCI) took aim at one of the most fragmented service industries in North America: funeral homes and cemeteries.
Starting in the 1960s, SCI moved quickly to buy up small, independent operators that lacked scale, succession plans, or the resources to modernize. These were legacy businesses—family-run, community-based, and operationally isolated.
The company didn’t rebrand everything. Instead, it kept local names and relationships intact while quietly plugging each acquisition into a centralized back-end system. Everything from accounting and insurance to pre-need planning and procurement was standardized and controlled from headquarters.
Centralized operations brought down costs, and bulk buying increased margins. In 2013, SCI acquired Stewart Enterprises, which was the second-largest provider at the time. At December 31, 2025, SCI operated 1,485 funeral service locations and 500 cemeteries across 44 states, eight Canadian provinces, the District of Columbia and Puerto Rico, and the roll-up continues: it spent $101.3 million in 2025 acquiring 22 funeral locations and two cemeteries.
Rollins Inc. (Orkin Pest Control)
Rollins Inc. executed a disciplined and scalable roll-up strategy in the pest control industry. Beginning in the 1960s and accelerating in the decades that followed, the company focused on acquiring small, regionally dominant pest control firms—most of them family-run with loyal customer bases and limited growth infrastructure.
Rather than overhauling every acquisition, Rollins brought them into a centralized system under Orkin, its flagship brand. It standardized routing, scheduling, and customer service tools while consolidating back-office functions like billing, IT, and HR. This allowed technicians to stay in the field while corporate handled the overhead.
The company targeted firms before they attracted broader buyer interest, keeping multiples low and integrations fast. While most acquisitions were folded into the Orkin brand, Rollins retained local names in certain markets to preserve goodwill. The approach still drives results: Rollins reported 2025 revenue of $3.8 billion, up 11.0%, with 4.1 points of that growth from acquisitions after investing $310 million in deals during the year.
Why roll-ups fail
Silver bullets do exist in M&A, but they’re remarkably rare.
So much positive material has been written about roll-ups that it’s easy to be convinced that this is a strategy where it is impossible to fail.
That just isn’t the case.
Paul Carroll and Chunk a Mui's study of 750 major business failures, published in Harvard Business Review in 2008, found that more than two-thirds of roll-ups failed to create any value for investors. The pattern has not changed. Envision Healthcare, a physician-practice roll-up that KKR bought for $9.9 billion in2018, filed for Chapter 11 in May 2023 with about $7.7 billion of debt.
The reasons for these failures usually fall under one of the following categories:
- Integration difficulties: As this article states, all things being equal, five smaller integrations usually means approximately five times the integration challenges as a company five times the size. This needs to be accounted for at the outset.
- Lack of benefits to scale: Not all industries have benefits to scale. The HBR article in the paragraph above mentions the funeral industry, where benefits to scale can only be enjoyed at a local level, and even then, they’re questionable.
- Failure to account for downturns and rate shocks: Most roll-up strategies are built on steady economic projections and cheap debt. The 2020 pandemic and the 2022 to 2024 rise in borrowing costs both exposed roll-ups whose debt loads only worked in a benign market.
- Overpaying for acquisitions: In an effort to close deals faster as part of a larger strategy, acquirers may be forced to overpay. This is also an issue as target companies become aware of the roll-up strategy. Overpaying destroys value in the overall strategy, just as it does in a standard acquisition. Regulatory scrutiny: Serial acquisitions in one market draw antitrust attention. In May 2025 the FTC finalized an order against Welsh Carson over what it called a roll-up scheme that bought nearly every large anesthesia practice in Texas; the firm must now notify the FTC before certain future physician-practice acquisitions.
Frequently asked questions
What’s the difference between a roll-up and a traditional acquisition?
A traditional acquisition typically involves a company buying another to expand into a new market or gain specific assets. A roll-up strategy, on the other hand, involves acquiring multiple smaller businesses in the same industry to consolidate a fragmented market, create scale, and improve operational efficiency.
What industries are best for roll-up strategies?
The best industries for roll-up strategies are fragmented service industries revenue and owners near retirement: dental, veterinary, HVAC, home health, physical therapy, funeral services, landscaping and auto repair. In each, no single company holds a large market share and billing, procurement and marketing can be centralized. PitchBook counted 55 private equity HVAC deals in 2024, the most since at least 2017, and the ADA reports more than 1 in 4 US dentists within 10 years of graduation were DSO-affiliated in 2024.
Why do investors prefer roll-up strategies?
Investors prefer roll-up strategies for three reasons. A roll-up buys small companies at low EBITDA multiples and sells the combined platform at a higher one (multiple arbitrage). It raises margins through shared back office, procurement and marketing. And it grows revenue faster than any one acquired company could alone. McKinsey found programmatic acquirers, which close several small deals a year, earned a median excess shareholder return of 2.3% over the decade to 2022.
How long does a typical roll-up strategy take?
Timelines vary, but a full roll-up strategy can take 3 to 7 years. This includes identifying targets, negotiating deals, integrating operations, and scaling the platform before an exit.
Key takeaways
- Roll-ups work best in industries with many small players, minimal consolidation, and where scale drives cost and margin advantages (e.g., dental, HVAC, veterinary, daycare, funeral services).
- Roll-ups unlock value through economies of scale, operational synergies, increased market exposure, and lower cost of capital for the larger combined entity.
- Value doesn’t come from the acquisitions alone—it depends on careful planning, disciplined deal execution, cultural and operational fit, and robust integration.
To paraphrase Warren Buffett, when answering a University of Florida audience about what steps they needed to take to be successful investors:
You don’t need to do anything really earth-shattering. You just need to consistently do lots of small things right.
This is the logic that underpins a roll-up strategy:
Consistently make smaller value-adding acquisitions, and your company will almost certainly outperform the market over the long term.
However, on balance, closing more deals means more pitfalls for acquirers. Anyone undertaking a roll-up strategy needs to allocate significant resources for planning, due diligence, and post-merger integrations.
DealRoom has already helped dozens of companies with their roll-out strategies. Talk to us today about how we can add value for you as you implement your planned roll-out strategy.