




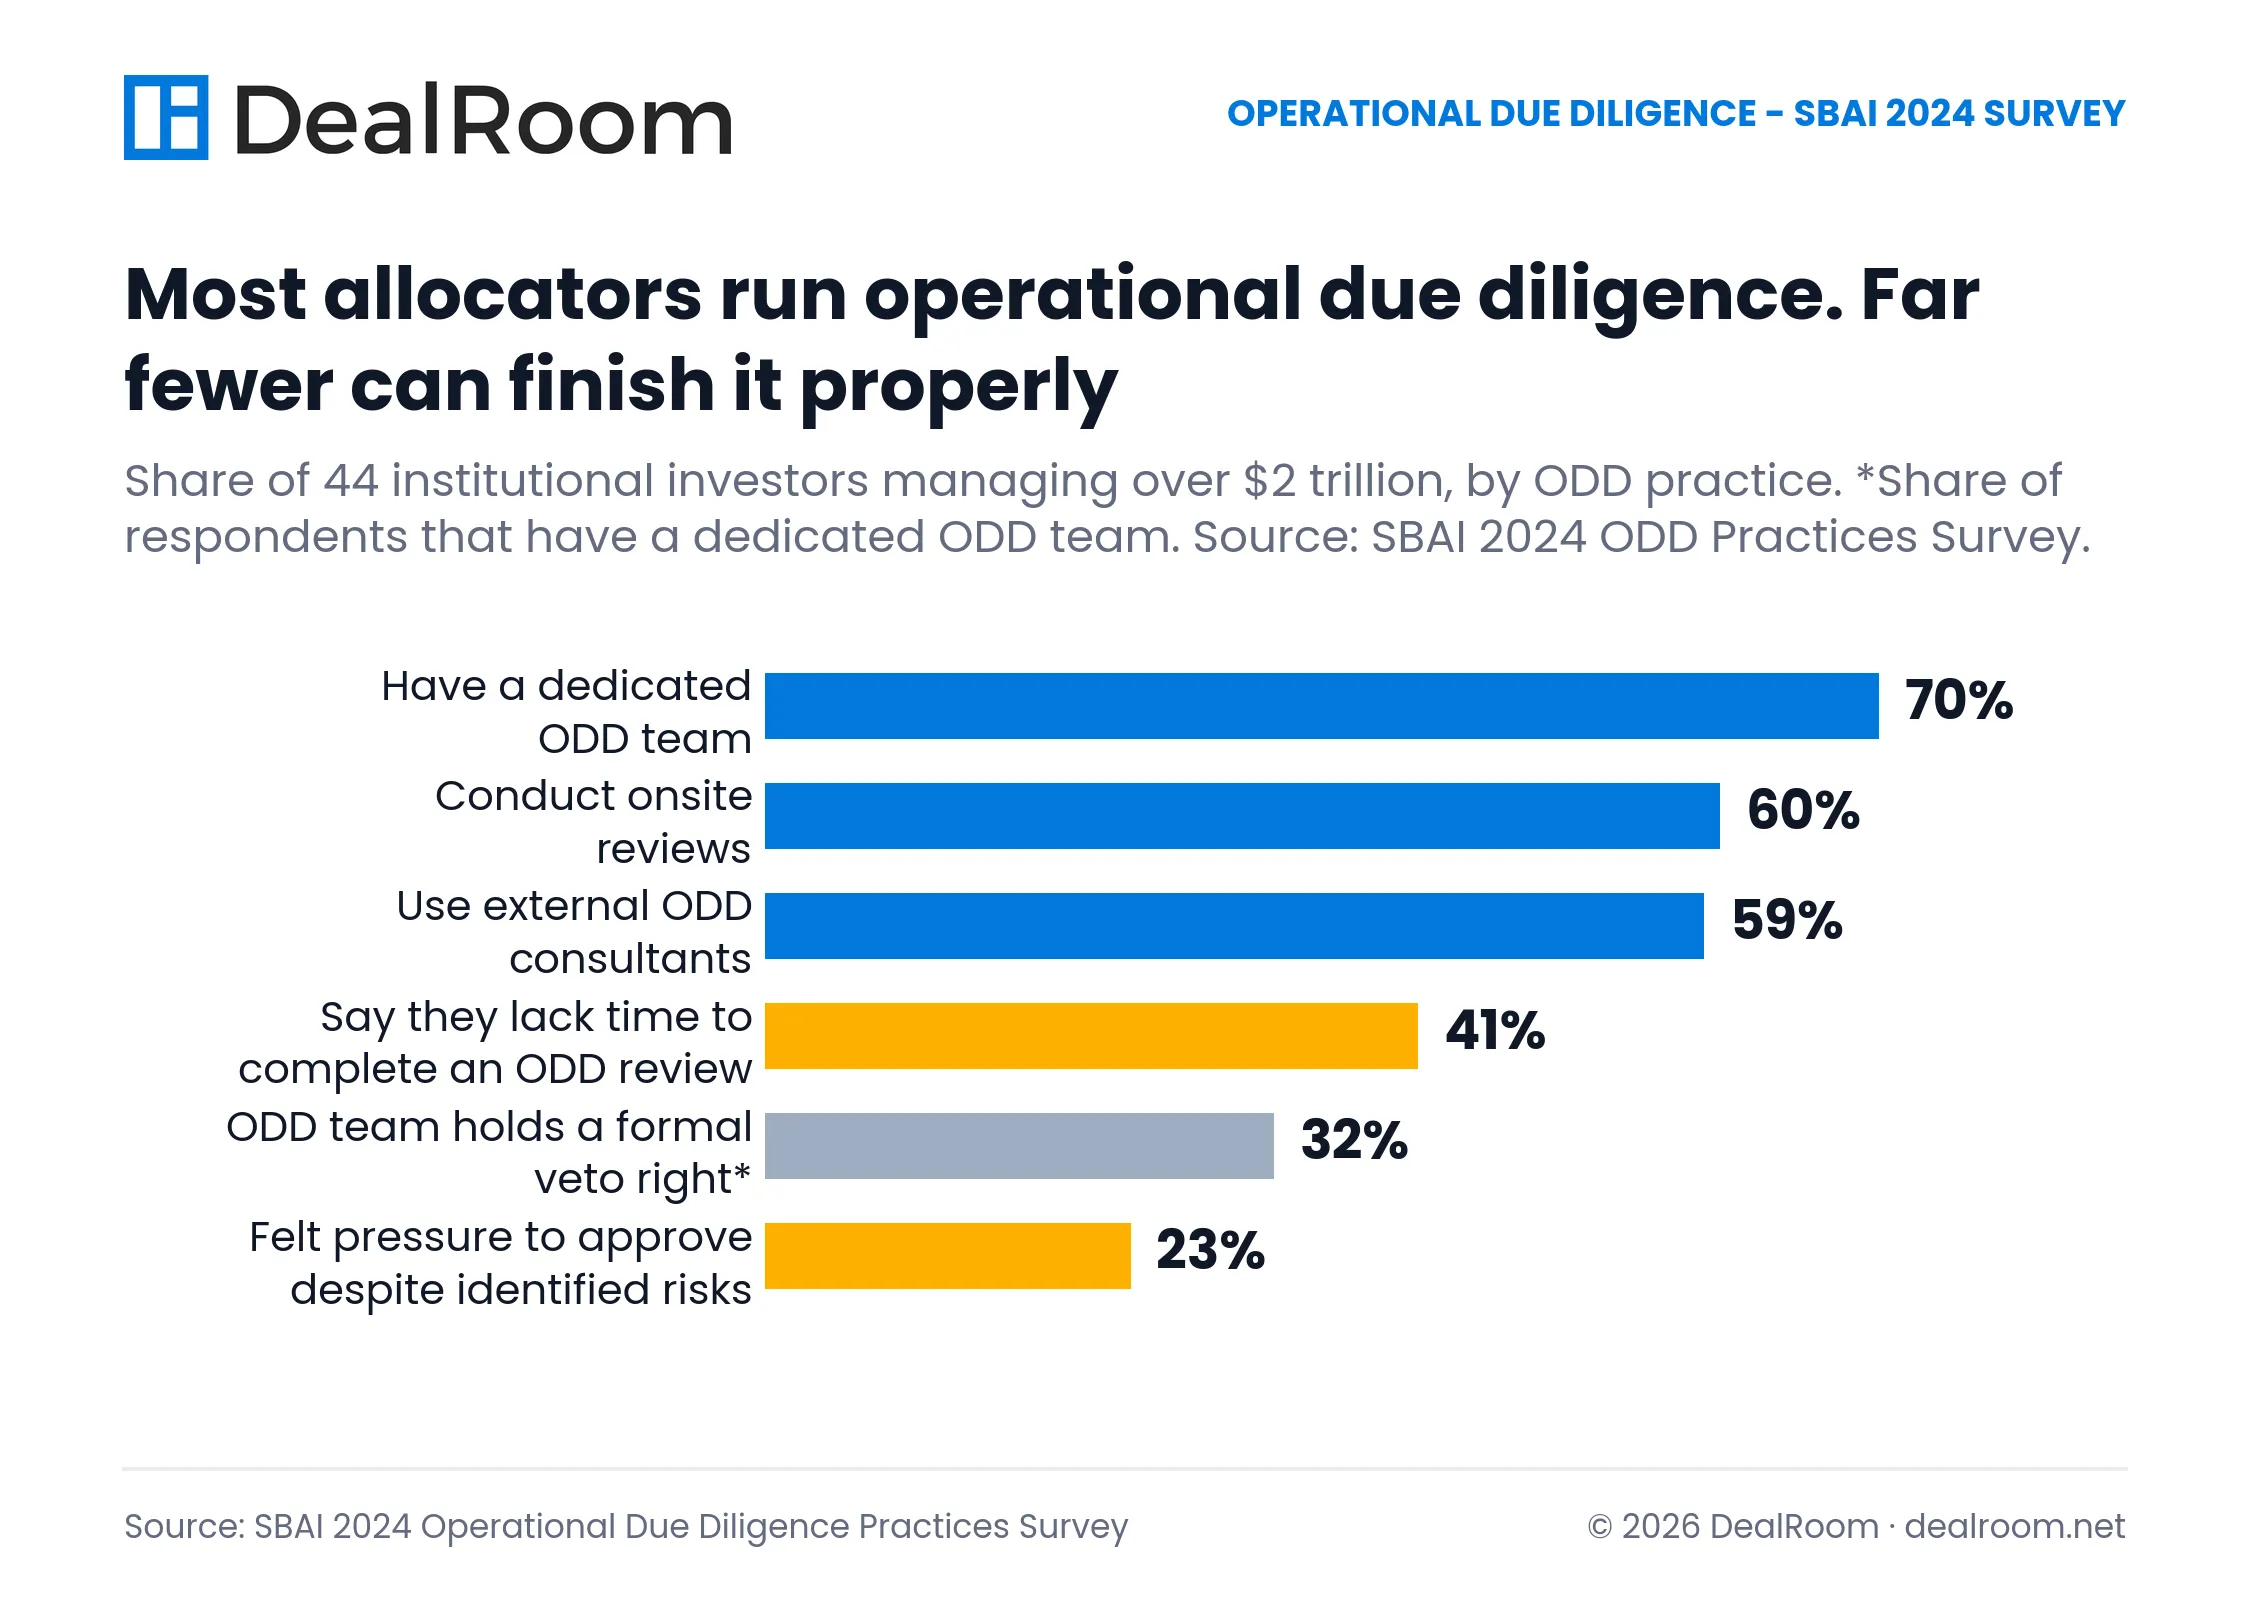
Forty-one percent of institutional allocators report that they do not have sufficient time to research and complete an operational due diligence review; nearly one-quarter have felt pressure or coercion to accept an allocation despite knowing risks, according to the Standards Board for Alternative Investments’ 2024 survey of 44 investors overseeing $2+ trillion of assets. That is the environment in which hedge fund due diligence is performed, and it’s why the mistakes that make the news are virtually never failures of analysis.
I’ve been building software for diligence teams for over a decade and interviewed over 400 practitioners on the M&A Science podcast. I’ve noticed a common theme in diligence conducted by funds that reflects diligence in corporate transactions: it’s the simple questions that uncover issues, not the clever ones. Did someone actually speak to the administrator? Did someone read the audit opinion, I don’t just know an audit opinion exists? Below is how the discipline breaks down, where each subset belongs and where you’ll find the red flags. Our hedge fund investment due diligence checklist turns it into an actionable playbook.
What is hedge fund due diligence?
Hedge fund due diligence is traditionally defined as the research exercise an allocator conducts prior to, and throughout, an investment in a hedge fund manager. Due diligence covers both the investment opportunity being presented as well as the business underpinning it. The two areas are commonly referred to as separate workstreams (each one answers different questions):
Investment due diligence (IDD) probes whether the manager can make money for you, and whether the return stream being presented is indeed what it purports to be. Areas such as strategy, process, portfolio construction, risk management, attribution and capacity all fall under this heading.
Operational due diligence (ODD) asks whether the business behind those returns actually works, and whether the assets exist. Administrator, auditor, custody, valuation, cash controls, compliance, regulatory filings, service provider verification and all the other areas required to operationalize a hedge fund sit in this bucket.
Legal and compliance review is generally housed inside ODD in most allocator due diligence frameworks. Environmental, social and governance review is treated as its own top-level section rather than folding into either workstream: see Section 19 of the ILPA questionnaire, or AIMA's responsible investment DDQ module.
The two sides are asymmetrical: ODD is the half that runs short of time, and the half that catches fraud.
The frameworks allocators actually use
Three documents do the heavy lifting in this market.
The Hedge fund industry standard due diligence questionnaire is the Alternative Investment Management Association’ s Illustrative Questionnaire for the Due Diligence of Investment Managers. The first edition was published in 1997, and a revised edition was published in 2025. Over 100 new questions were added across the modules in the 2025 revision, which also reduced total question count for most users. A private markets strategy module was added as was deeper coverage on performance presentation, outsourcing and technology risk, counterparty and leverage risk, liquidity management and expense disclosure.
The Standards Board for Alternative Investments' Alternative Investment Standards describe 28 standards related to disclosure, valuation, risk management, fund governance and shareholder conduct. Given that SBAI's list of signatories include over 250 institutional investors and asset managers with collective assets under management of approximately $11 trillion, the Standards are likely to represent a practical baseline, rather than a desirable goalpost. However, its Due Diligence Checklist helpfully divides preparing for ODDs into pre-, during and post-meeting phases, and assigns service provider verification and principal background checks to the post-meeting phase.
You should know about ILPA's Due Diligence Questionnaire 2.0 so you don't misapply it. ILPA makes clear that the questionnaire is tailored to established private equity managers. Also, the asset-class specific modules ILPA is developing focus on real estate, private credit and infrastructure, not hedge funds.
Investment due diligence: what to test
Manager pitches are designed to convince. Due diligence is there to stress-test them, not by accepting the strategy story as read, but by verifying each assertion against the underlying process, numbers and contract terms that can't easily be twisted. The seven areas below are where this testing takes place.
- Strategy and edge. What’s the repeatable source of return and who else is running it? The goal is to independently assess skill vs. factor exposure that’s being packaged and sold to you at a performance fee.
- Investment process. Who comes up with ideas, who sizes them, who kills them, and is any of that written down? If your process lives only in the founder’s head, it won’t survive the founder.
- Portfolio construction. Concentration limits, position sizing rules and ranges for both gross and net exposure. These rules determine whether a bad call blows up your drawdown or your fund, which is why they should be tested separately from stock picking.
- Risk management. If risk is a standalone group or part of the portfolio manager's responsibility, who runs what stress tests and who has the authority to force a de-risking? Standards 9 through 20 of SBAI’s playbook cover portfolio, liquidity, market, counterparty and operational risk.
- Attribution and persistence. Are returns broken down in a way that you can find the stated edge? Does the pattern of persistence hold across multiple rolling periods and not just one vintage? If not, then either the attribution is wrong or their pitch is wrong.
- Liquidity terms matching. Do redemption terms reflect the liquidity of the underlying portfolio? What gates, side pockets or lockups are available? In its 2026 examination priorities, the SEC highlighted private funds with lengthy investment lock ups, so they see the mismatch too.
- Leverage, counterparty and key person risk. Difference between gross and net leverage, source of financing, margin requirements and rehypothecation. Prime broker concentration and exposure on downgrade. Does a key-man clause exist and what is business continuity when the main asset walks out the door each night?
Operational due diligence: the section that catches frauds
Most fund failures are investment losses. Most fund frauds are operational failures masquerading as investment losses (a fabricated NAV, a captive administrator, a compliance function that answers to the person it’s charged with monitoring). Operational due diligence is designed to identify the failure mode before it bites investors. Below are a few items pairing each control with the tell-tale red flag that it’s not really there.
Independent administrator and NAV verification. Red flag: self-administration, a related party administrator or an administrator that benchmarks NAV against the manager’s own performance. Request a statement delivered directly to you from the administrator, not one routed through the manager.
Audit firm quality and opinion. Red flag: an audit firm that’s too small to realistically be auditing the fund, a qualified opinion, late financial statements or an unexplained change in auditor. Read the audit opinion instead of merely asking if there’s an audit.
Custody and prime brokerage. Red flag: assets maintained with a related broker-dealer, the manager unilaterally able to move cash or a single prime broker without a backup.
Valuation policy and Level 3 assets. Red flag: manager-operated pricing models for an illiquid book, no valuation committee, recent mid-life switch of pricing source or no visible segregation between valuation and portfolio management. SBAI Standards 5 through 8 require segregation explicitly.
Cash controls and segregation of duties. Red flag: same person can initiate and approve a wire, no dual authorization, any commingling of personal and fund accounts.
Compliance program and chief compliance officer. Red flag: CCO acting as CFO, COO or portfolio manager, no annual compliance review, policies obviously cut-and-pasted from a template.
Regulatory registration. Red flag: operating without registration where required. Previous disciplinary events reported to IAPD or on Form PF have not been filed. In December 2024, the SEC settled charges with seven private fund advisers who together paid $790,000 for repeatedly failing to file Form PF. Form PF is an inexpensive filing to prepare and submit so repeated failures to file should raise a red flag.
Business continuity and cybersecurity. Red flag: no evidence of a tested business continuity plan. The firm only has one office. Firm does not use penetration testing, multi-factor authentication and vendor security reviews.
Service provider verification and background checks. Red flag: not directly speaking to listed service providers. No disclosure of any suits against principals. Prior fund closures that are not mentioned in the biography.
Side letters and most-favoured-nation terms. Red flag: watch out for undisclosed preferential liquidity or fee terms granted to other investors. The SEC’s 2026 exam priorities include the differential treatment of investors, such as through the use of side letters, as a review area for advisers that are new to advising private funds.
Why operational due diligence carries the weight it does
The commonly quoted statistic originates from Capco's 2003 report, Understanding and Mitigating Operational Risk in Hedge Fund Investments. That report looked at a database of over 100 fund failures and attributed 50% of those failures to operational risk (versus 38% to investment related risk). Of the operational failures, 41% were due to misrepresentation of investments and 30% to misappropriation of funds. This study was conducted more than 20 years ago, and its methodology has not been repeated since. Consider it as the genesis of the claim rather than as reliable data.
The contemporary version is the SBAI’s 2024 survey, and it shows how the work is actually resourced: 70% of allocators have a dedicated ODD team, with teams of one to four people being the most common size at all asset levels. 59% use external consultants, and 32% of those with dedicated teams have formal veto rights over an allocation.
Madoff continues to be the benchmark case because all three lines of defense failed, and each failure was evident from outside the firm. There was no independent administrator. The auditor was a storefront firm that had no ability to audit a firm of that size. According to the SEC’s litigation release against auditor David Friehling, he “did not perform procedures to confirm that the securities BMIS purportedly held on behalf of its customers even existed.” Custody was conducted internally. According to the SEC’s own inspector general report, the SEC conducted two investigations and three examinations of Madoff’s investment advisory business based on credible complaints and “at no time did the SEC ever verify Madoff’s trading through an independent third-party.”
This trend continued past 2008. In March 2025, the SEC charged Momentum Advisors and two of its officers with failing to supervise more than 100 debit card transactions totaling approximately $223,000 that were misappropriated from a fund, and also found that none of the fund audits were ever performed. In the Allianz Global Investors Structured Alpha case, portfolio managers manipulated risk reports provided to investors by changing one investor's projected loss of 42.15% to 4.15%. Billions of dollars were lost by investors, with Allianz Global Investors and its parent agreeing to pay more than $5 billion in restitution to victims. Each of those situations was an ODD finding, rather than an IDD finding.
What the current market looks like
Hedge fund industry capital peaked at an all-time high of $5.22 trillion in the first quarter of 2026, according to HFR. There were 166 hedge fund launches and 129 liquidations in the quarter. Average fees are running at 1.32% management and 15.78% incentive.
The SEC’’s private funds statistics reported 9,940 hedge funds with gross asset value of $13.9 trillion as of the third quarter of 2025. Those funds are reported by 1,834 registered advisers. Adviser filings are public. Cross checking a manager’s Form ADV against what they tell you is the cheapest verification step in the process.
Running the process
Here is an example of a workable sequence:
- Distribute the questionnaire and request supporting documents.
- Perform the IDD and ODD simultaneously with different owners. (If one owner performs both, he will inevitably short-change the ODD when pressed for time.)
- Conduct the onsite. Most survey respondents (60% of SBAI) still perform these visits either in-house or with the assistance of a consultant.
- Follow-up independently after the meeting. Call the administrator and the auditor. Perform background checks on the principals and cross-check registrations with IAPD.
Verification is typically where the process fails, because it occurs after most of the interesting conversations have concluded and the allocation decision has built social momentum. Making verification explicit through named owners and documentation is typically the highest-return change any allocator can implement. Documentation is important too. Our article on building a due diligence report describes how to format findings so they're useful to a committee.
Our hedge fund investment due diligence checklist includes things like alternative-investment readiness, a stress-tested operations resilience check and an auditable trail of decision-making Q&A (questions, comments and approvals). Our due diligence process guide covers the six steps in the process in more detail, and our due diligence questionnaire guide covers the DDQ format and how to score answers.
Frequently asked questions
What does operational due diligence for hedge funds involve?
Operational due diligence refers to the examination of a fund's underlying business operations that support its returns: administrator, auditor, custody, valuation policy, cash controls, compliance program, regulatory filings, business continuity, cybersecurity and service providers. In other words, does the money exist, and is the operation trustworthy? It’s different from investment due diligence, which focuses on whether the manager can generate returns.
What’s the difference between IDD and ODD?
Investment due diligence covers strategy, process, portfolio construction, risk management and performance attribution. Operational due diligence covers the business and control environment. Both are required, but ODD is historically where fraud is discovered.
What’s a DDQ?
A due diligence questionnaire (DDQ) is the standard form an allocator will send to a manager to request information in a consistent format. AIMA’’s Illustrative Questionnaire for the Due Diligence of Investment Managers, updated in 2025, is the benchmark version for hedge funds. For private equity, ILPA's DDQ 2.0 serves as its equivalent, and ILPA has stated that it’s best-suited for legacy private equity managers.
What are the biggest red flags in hedge fund due diligence?
Lack of independent administrator or one that is affiliated, an auditor that’s too small for the size of the fund, a chief compliance officer (CCO) also has an investment or finance role, manager values illiquid positions using their own model with no committee oversight, a single individual with ability to initiate and approve wires, missing regulatory filings and named service providers that were never independently verified.
How much time does hedge fund due diligence take?
Not surprisingly, there is no credible published average, and any number you read should be viewed with skepticism. What IS revealing is that SBAI’s 2024 survey found that 41% of allocators report not having enough time to complete an ODD review. This implies the constraint is driven by calendar pressure, not a recognized rule-of-thumb duration.
Can an operational due diligence team veto a decision?
In some cases, yes. The SBAI’s 2024 benchmarking survey discovered that 32% of allocators with stand-alone ODD teams possess formal veto rights while an additional 15% hold unofficial veto rights (meaning they have the power to veto but it is not formally documented as such). About 38% do not have veto power. Of those who have some form of veto right, 73% use it either rarely or no more than annually.