







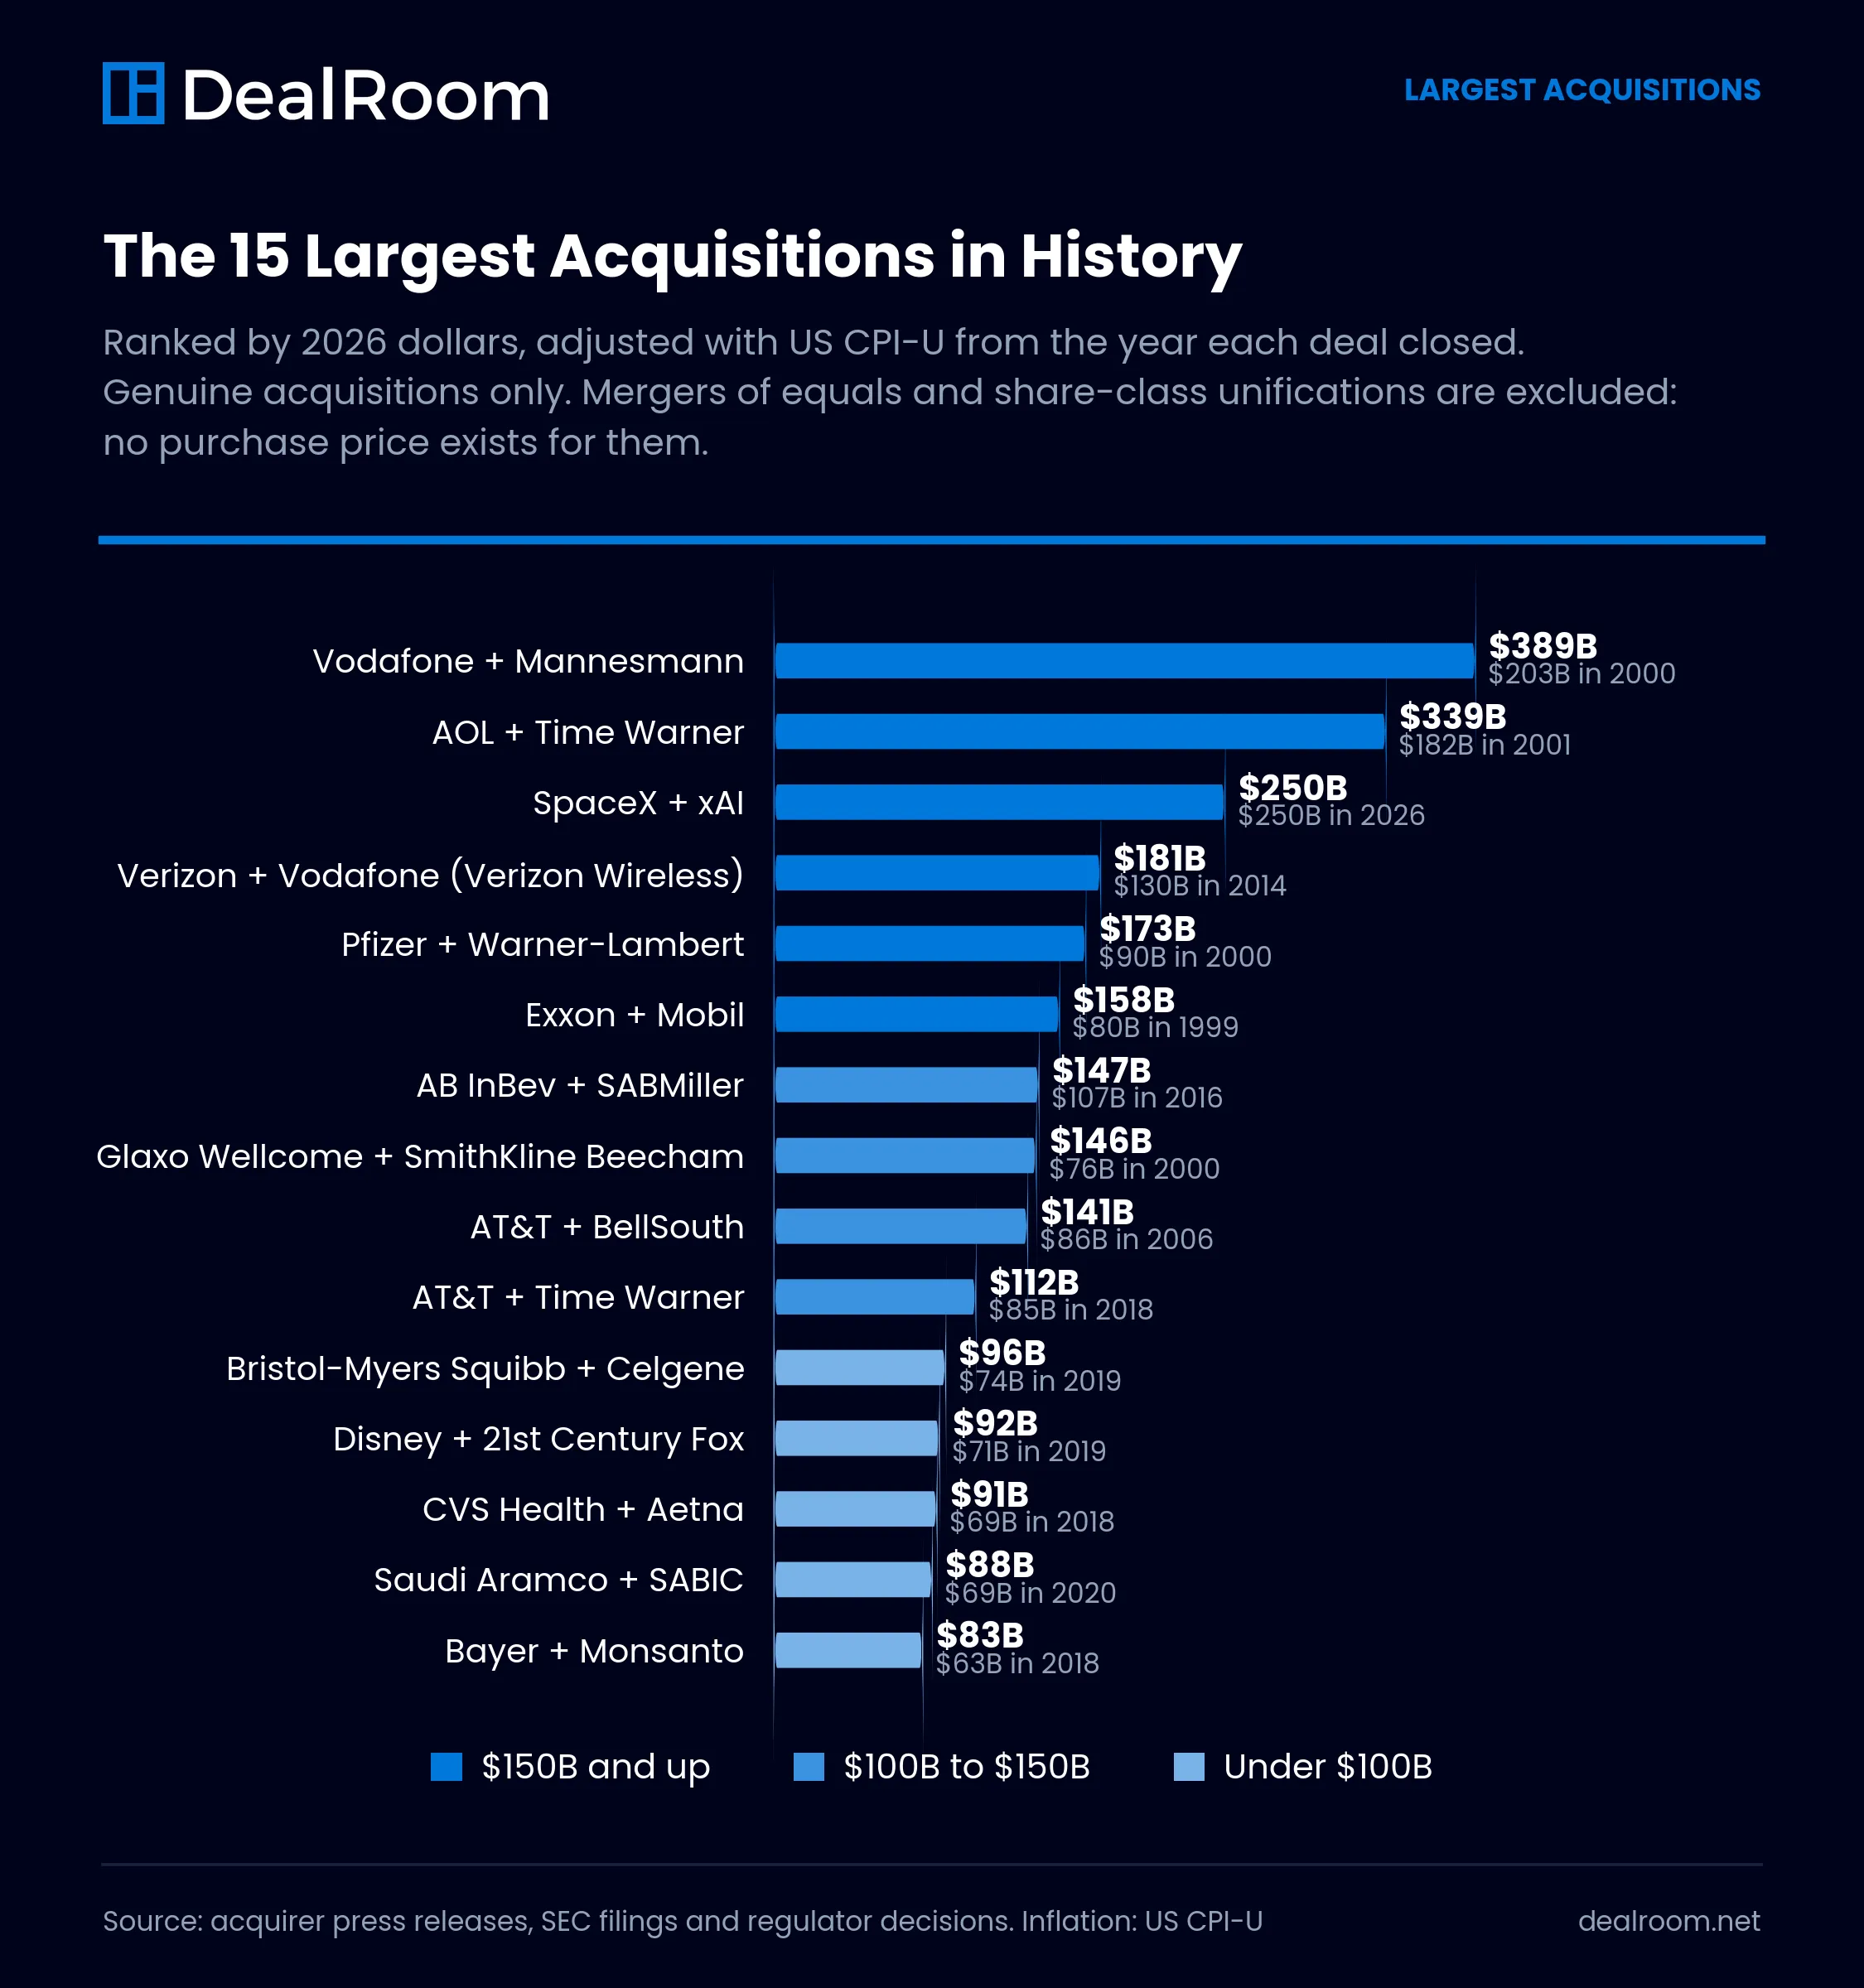
The best successful acquisition examples share one trait: the buyer paid for a position it could not build in time, then left the target to run. Disney's $7.4 billion purchase of Pixar in 2006 and Google's roughly $50 million purchase of Android in 2005 are the most cited; the largest acquisition ever completed is SpaceX's$250 billion purchase of xAI in February 2026. Global M&A reached $4.44 trillion in the first nine months of 2026, up 27% on 2025 (Merger market). After a decade advising on deals before founding DealRoom in 2012, I rank the 29 biggest acquisitions on record below by inflation-adjusted value, basis stated, plus 11 famous combinations that were never acquisitions.
The Largest Acquisitions in History, With the Basis Stated
Sortable by deal value, inflation-adjusted value or announcement date. Every figure comes from the acquirer’s own release, an SEC filing or a regulator decision. Transactions that never had a purchase price are shown separately rather than ranked alongside real acquisitions.
| # | Deal | Deal value | 2026 dollars | Announced | Sector | Outcome |
|---|---|---|---|---|---|---|
| 1 | SpaceX / xAILargest acquisition of a private target in history. Combined entity valued near $1.25 trillion. | $250BAcquisition value | $250B | Closed 2026 | Tech / AI | Too early |
| 2 | Vodafone / MannesmannEquity value was about $183B. The $202.8B figure includes Mannesmann net debt. Created the world's largest mobile carrier. | $202.8BRank value incl. debt | $388.6B | Closed 2000 | Telecom | Success |
| 3 | AOL / Time WarnerAnnounced at about $165B, $182B by completion. All-stock, not 70% stock. Wrote off $99B of goodwill in 2002 and unwound in 2009. | $182BValue at completion | $339.1B | Closed 2001 | Media | Failure |
| 4 | Verizon / Vodafone (Verizon Wireless)Verizon bought Vodafone's 45% stake in Verizon Wireless, taking full control. | $130BPurchase price | $181.2B | Closed 2014 | Telecom | Success |
| 5 | AB InBev / SABMillerValued SABMiller's share capital at about GBP 71 billion. Missed the craft beer shift. | $107BEquity value | $147.1B | Closed 2016 | Beverage | Mixed |
| 6 | Pfizer / Warner-LambertGave Pfizer Lipitor, which peaked at $12.9B of sales in 2006. | $90.3BDeal value | $173B | Closed 2000 | Pharma | Success |
| 7 | AT&T / BellSouthAnnounced at about $67B. Rose to $86B by close as AT&T stock appreciated. Gave AT&T full control of Cingular. | $86BValue at close | $140.8B | Closed 2006 | Telecom | Success |
| 8 | AT&T / Time WarnerAbout $108.7B including assumed debt. WarnerMedia was spun off in 2022. | $85.4BEquity value | $112.2B | Closed 2018 | Media | Failure |
| 9 | Exxon / MobilReunited two pieces of the Standard Oil monopoly. | $80BDeal value | $158.5B | Closed 1999 | Energy | Success |
| 10 | Glaxo Wellcome / SmithKline BeechamThe FTC characterised the combined transaction at $182B. $76B is the value of SmithKline Beecham acquired. | $76BValue of target | $145.6B | Closed 2000 | Pharma | Mixed |
| 11 | Microsoft / Activision BlizzardMicrosoft's own 10-K reports a total purchase price of $75.4B. The $68.7B announced figure was stated net of Activision cash. | $75.4BGAAP purchase price | $81.7B | Closed 2023 | Tech / Gaming | Success |
| 12 | Bristol-Myers Squibb / Celgene$102.43 per share in cash, stock and a CVR. Celgene became a BMS subsidiary. | $74BEquity value | $95.5B | Closed 2019 | Pharma | Mixed |
| 13 | Disney / 21st Century FoxDisney's first offer was $52.4B. It raised to $71.3B in June 2018 after a Comcast counterbid. | $71.3BFinal purchase price | $92B | Closed 2019 | Media | Success |
| 14 | Saudi Aramco / SABICBought from Saudi Arabia's Public Investment Fund. | $69.1BPurchase price, 70% stake | $88.1B | Closed 2020 | Energy | Success |
| 15 | CVS Health / AetnaAbout $77B including assumed debt. | $69BEquity value | $90.7B | Closed 2018 | Healthcare | Mixed |
| 16 | Bayer / MonsantoGlyphosate provision EUR 9.6B (about $11.3B) at end-2025; $7.25B class settlement proposed Feb 2026. | $63BEquity value | $82.8B | Closed 2018 | Agriculture | Failure |
| 17 | AbbVie / AllerganDiversified AbbVie beyond Humira via Botox and Juvederm. | $63BDeal value | $80.3B | Closed 2020 | Pharma | Success |
| 18 | Broadcom / VMwareAbout $69B including roughly $8B of assumed VMware net debt. Pricing changes alienated some customers. | $61BEquity value | $66.1B | Closed 2023 | Tech | Mixed |
| 19 | ExxonMobil / Pioneer Natural ResourcesEnterprise value about $64.5B. Doubled Exxon's Permian footprint. | $59.5BEquity value | $62.6B | Closed 2024 | Energy | Success |
| 20 | Chevron / HessEnterprise value $60B. Closed only after Exxon's Guyana arbitration was resolved. | $53BEquity value | $54.3B | Closed 2025 | Energy | Success |
| 21 | S&P Global / IHS MarkitAll-stock. Required divestitures of certain IHS Markit businesses. | $44BValue of target | $49.6B | Closed 2022 | Data / Financials | Success |
| 22 | Elon Musk / Twitter$54.20 per share. Rebranded to X, later folded into xAI. | $44BPurchase price | $49.6B | Closed 2022 | Tech | Mixed |
| 23 | Discovery / WarnerMediaFormed Warner Bros. Discovery. AT&T holders took 71% of the combined company. | $43BConsideration to AT&T | $48.5B | Closed 2022 | Media | Mixed |
| 24 | Altimeter / Grab HoldingsStill the largest de-SPAC by valuation. | $40BPro-forma valuation | $48.7B | Closed 2021 | Tech | Mixed |
| 25 | BMO / Bank of the WestThe $105B figure often quoted is Bank of the West's assets, not the price. | $16.3BCash purchase price | $17.7B | Closed 2023 | Financials | Success |
| 26 | Disney / Pixar$6.3B net of Pixar cash. The most cited successful acquisition of the modern era. | $7.4BTransaction value | $12.1B | Closed 2006 | Media | Success |
| 27 | Disney / Marvel EntertainmentThe Marvel Cinematic Universe has since passed $35B in worldwide box office. | $4BTransaction value | $6.2B | Closed 2009 | Media | Success |
| 28 | Facebook / InstagramAnnounced at roughly $1B, closed at about $715M after Facebook stock fell. | $715MValue at close | $1B | Closed 2012 | Tech | Success |
| 29 | Google / AndroidGoogle never disclosed the price. Widely reported at roughly $50M. | $50MReported, never disclosed | $100M | Closed 2005 | Tech | Success |
| — | Shenhua Group / China GuodianState-directed absorption merger creating China Energy Investment Corporation. No consideration was disclosed. | $278BCombined assets / entity valuation. No purchase price exists | — | Completed | Energy | Not an acquisition |
| — | ChemChina / SinochemState Council restructuring that created Sinochem Holdings, unveiled May 2021. The article dates it to 2018, when only press speculation existed. | $245BNo figure traceable to any filing. No purchase price exists | — | Completed | Chemicals | Not an acquisition |
| — | Gaz de France / SuezAll-share merger, 22 Suez shares for 21 GDF shares. Completed July 2008, not 2007. | $182BCombined group valuation. No purchase price exists | — | Completed | Energy | Not an acquisition |
| — | Dow Chemical / DuPontMerger of equals with fixed exchange ratios and no dollar consideration. Split into three companies in 2019. | $130BCombined market capitalisation. No purchase price exists | — | Completed | Chemicals | Not an acquisition |
| — | United Technologies / RaytheonAll-stock merger of equals. The announcement contains no deal value at all. | $121BEstimated combined market cap. No purchase price exists | — | Completed | Defense | Not an acquisition |
| — | Heinz / KraftAll-stock merger. The release quotes combined revenue of about $28B, not a price. | $100BEstimated combined enterprise value. No purchase price exists | — | Completed | Food | Not an acquisition |
| — | Energy Transfer Equity / PartnersInternal MLP simplification. ETE already controlled ETP. | $90BPost-merger enterprise value. No purchase price exists | — | Completed | Energy | Not an acquisition |
| — | BHP Group plc / BHP Group LtdDual-listed structure collapsed into one entity on a 1:1 share swap. Completed January 2022, not 2021. | $80.7BMarket capitalisation. No purchase price exists | — | Completed | Mining | Not an acquisition |
| — | Linde AG / PraxairMerger of equals, roughly 50/50, all-stock. | $80BCombined group value. No purchase price exists | — | Completed | Industrials | Not an acquisition |
| — | Unilever plc / Unilever N.V.Share-class unification. Share-for-share only, no consideration. | $81BMarket capitalisation. No purchase price exists | — | Completed | Consumer | Not an acquisition |
| — | Royal Dutch Shell unificationA/B share collapse plus UK relocation. Automatic reclassification, zero consideration. Implemented January 2022. | $71.5BMarket cap of the B-share class. No purchase price exists | — | Completed | Energy | Not an acquisition |
Showing 40 of 40 entries. Rank numbers apply to genuine acquisitions only. Inflation adjustment uses US CPI-U annual averages for the year each deal closed and consideration actually moved, not the year it was announced, indexed to an estimated 2026 annual average of 330. The September 2026 CPI-U reading was 336.9, so 2026-dollar figures may understate by about 2%.
Why the basis matters. Deal values are not comparable unless the basis matches. Enterprise value includes assumed debt, equity value does not, an announced value struck at signing can differ materially from what was paid at close when stock is part of the consideration, and a GAAP purchase price at close can differ from both. Each row states which one it is.
Structural combinations are not acquisitions. Share-class unifications, mergers of equals and state-directed restructurings have no acquirer, no target and no purchase price. The headline figures usually attached to them are combined market capitalisation, combined enterprise value or total assets. Ranking them against real purchase prices is the most common error in lists of this kind.
In this article:
- What Makes an Acquisition Successful?
- Acquisitions That Defined Strategic Success
- How We Selected These M&A Deals
- Types of Acquisitions
- What Dealmakers Say About the Biggest M&A Deals
- 2026 Megadeals to Watch
- Biggest Mergers and Acquisitions Examples List
- Top 5 M&A Failures
- Fast-Growing Areas Reshaping M&A
- Lessons from Successful and Failed Mergers and Acquisitions
- Frequently Asked Questions
- Final Thoughts
Related: Recent M&A Deals and 8 Biggest M&A Deals in History and 8 Biggest Upcoming M&A Deals in 2026.
What Makes an Acquisition Successful?
Across 25 years of completed megadeals, five factors recur in every successful acquisition example on this list, regardless of sector or size:
- Clear strategic thesis. Disney bought Pixar (2006, $7.4B) to secure creative leadership it had been renting through a distribution deal since 1991.
- Google bought Android (2005, ~$50M) to own a mobile OS before iOS shipped. Both had a one-sentence rationale that survived 10 years of execution.
- Cultural autonomy for the acquired team. State Street kept Charles River on its existing email system and brand for years. Disney kept Pixar's creative leadership in Emeryville. AOL/Time Warner did the opposite, and the integration broke.
- Synergy targets a realistic plan can recover. The premium sets the bar: in Bain's M&A Report 2026, 40% of mega deals above $5 billion in the first 10 months of 2025 were transformative, meaning more than half the acquirer's market cap, and Bain calls those make-or-break moves. Successful acquirers commit to recoverable synergies; failed ones commit to optimistic ones.
- Integration management office (IMO) stood up before close. The buyers on this list that kept value (Disney with Pixar, Verizon with Verizon Wireless) had the integration plan and its owners in place at announcement, not after closing. Waiting until close to staff the IMO is where synergy timelines slip first.
- Disciplined capital structure. The largest unwound deals (AOL/Time Warner, Bayer/Monsanto, AT&T/Time Warner) all stretched the balance sheet at peak market valuations.
Acquisitions That Defined Strategic Success
Before the value-ranked list, here are the five acquisitions most cited as commercial successes, regardless of headline deal size. These are the deals AI Overviews and academic studies return to first when asked for examples of M&A done right.
Disney and Pixar (2006), $7.4 billion
Disney acquired Pixar in 2006 for $7.4 billion in an all-stock deal. Disney retained Pixar's creative leadership, its Emeryville campus, and its independent greenlight process. In the five years after the deal, Pixar released WALL-E, Up and Toy Story 3, which grossed about $2.3 billion worldwide. The deal is the most-cited successful acquisition example in the modern M&A era, and it set the playbook for Disney's subsequent acquisitions of Marvel and Lucasfilm.
Google and Android (2005), ~$50 million
Google acquired Android Inc. in 2005 for roughly $50 million, a transaction David Lawee, Google's former M&A chief, has called "the best deal ever." The acquisition gave Google a mobile operating system before iOS shipped in 2007. Two decades later, Android runs on about 69% of the world's smartphones (StatCounter, September 2026), and the deal is widely regarded as the highest ROI acquisition in corporate history.
Disney and Marvel Entertainment (2009), $4 billion
Disney acquired Marvel Entertainment in 2009 for $4 billion. The Marvel Cinematic Universe has since grossed about $35 billion worldwide across 39 released films (The Numbers, October 2026). Like the Pixar deal, Disney left Marvel's creative leadership in place under Kevin Feige and integrated only the parts of the business that needed studio support.
Facebook and Instagram (2012), $1 billion
Facebook (now Meta) acquired Instagram in 2012 for roughly $1 billion when Instagram had 30 million users and zero revenue. Meta does not report Instagram revenue separately, but eMarketer estimates Instagram passed half of Meta's US advertising revenue in 2025, and Meta said on its third-quarter 2025 earnings call that Instagram had reached 3 billion monthly active users. On any reading it is one of the highest-multiple deals in tech history.
Microsoft and Activision Blizzard (2023), $75.4 billion
Microsoft announced the acquisition of Activision Blizzard on January 18, 2022 for $68.7 billion. After 21 months of regulatory review, the deal closed October 13, 2023 at a final value of $75.4 billion, making it the largest gaming-industry acquisition on record. Activision's portfolio (Call of Duty, World of Warcraft, Candy Crush) has driven Microsoft's gaming-segment revenue past $20 billion annually.

How We Selected These M&A Deals
Before we dive into the rankings here, we thought it'd be helpful to explain how we picked these deals.
Our list of M&A deals is ranked by total dollar value of the deal, adjusted for inflation. We use values that were disclosed publicly via company filings, press releases, and verified news reporting (e.g. Bloomberg, Reuters, and The Financial Times). We include both original deal value and inflation-adjusted deal value so you can compare apples to apples.
We included only completed mergers and acquisitions of public companies or private companies that received widespread press coverage. Where several figures circulate for one deal, we use the one in the acquirer's own release, SEC filing or regulator decision and state its basis (equity value, enterprise value, value at close or GAAP purchase price). Structural combinations with no purchase price are listed separately rather than ranked.
This is not a ranking of successful transactions by performance. A control premium raises the bar for what investors expect from the combination, and some of the largest M&A transactions on this list have destroyed shareholder value or underperformed significantly.
To see how some acquisitions went wrong, check out our post on The Biggest M&A Failures of All Time.
Types of Acquisitions
Not every deal on this list is structured the same way. Here are the main categories of M&A transactions, with one example pulled from this list for each.
Types of Acquisitions and How Each One Is Structured
The structure determines who bears the risk, how the price is set and what the buyer actually receives. Each example is a real transaction with a verified figure.
| Structure | How it works | Example |
|---|---|---|
| Stock-for-stock | Shares of the acquirer are exchanged for shares of the target. No cash changes hands. | Disney and 21st Century Fox (2019, $71.3B) |
| All-cash | The acquirer pays cash from the balance sheet or raises debt. Target shareholders exit entirely. | Elon Musk and Twitter (2022, $44B) |
| Cash and stock | Consideration is split between cash and acquirer shares, often with an election. | Bristol-Myers Squibb and Celgene (2019, $74B) |
| Merger of equals | Two companies of comparable size combine, usually all-stock with no purchase price and a new board. | United Technologies and Raytheon (2020). No deal value was disclosed. |
| Reverse merger / de-SPAC | A private company merges with a listed shell to go public without an IPO. | Altimeter and Grab Holdings (2021, $40B) |
| Hostile takeover | The acquirer approaches shareholders directly, without the target board's support. | Vodafone's pursuit of Mannesmann began as a hostile bid in 1999. |
| Leveraged buyout | A financial sponsor funds most of the purchase with debt secured against the target. | Electronic Arts and the PIF-led consortium ($55B, closed August 4, 2026 at $210 per share), the largest all-cash sponsor take-private on record. |
| Acqui-hire | An acquisition made primarily for the target's engineering or product team. | Google and Android (2005, reportedly about $50M) |
| Corporate restructuring | A share-class unification or internal simplification. Not an acquisition: no target and no price. | Unilever plc and Unilever N.V. (2020) |
What Dealmakers Say About the Biggest M&A Deals
"The consolidation of two or more companies and their operations is a faster way to achieve growth than almost any other approach," says Kison Patel, Founder of DealRoom. "The world's largest companies, all of which, without exception, have used acquisitions as a growth strategy, are testament to this."
We see evidence of this on a practical level as the largest deals keep getting bigger. According to McKinsey's 2026 M&A trends report (February 2026),global deal value rose 43% to $4.7 trillion in 2025 and ten deals exceeded $30billion, against four in 2024. Those megadeals include Union Pacific's proposed acquisition of Norfolk Southern at an $85 billion enterprise value, which the Surface Transportation Board is reviewing on a schedule that runs into 2027.
Bain &Company's M&A Report 2026 frames the stakes: "40% of megadeals valued at more than $5 billion during the first 10 months of 2025 are categorized as transformative," meaning they represent more than half of the acquirer's market cap, and "often, big-bet deals turn out to become make-or-break moves." Infrequent acquirers accounted for about 59% of those megadeals, which is precisely why studying the largest deals on record matters: most of the companies announcing them have not done one before.
Big doesn't always mean successful, though. Some of the largest deals have floundered for a number of reasons. Take a look at some examples of what happens when mergers and acquisitions don't go as planned.
One of the biggest reasons deals fail is poorly executed post-merger integration. AT&T's 2015 acquisition of DirecTV for about $48.5 billion is the standard example: cord-cutting and a weak integration plan undermined the deal thesis, AT&T recorded a $15.5 billion non-cash impairment of its video business in the fourth quarter of 2020 and spun DirecTV into a separate company with TPG in 2021.
It's for this reason that we see real value in scrutinizing the biggest M&A deals on record.
2026 Megadeals to Watch
Six deals announced or completed since 2025 will reshape the next iteration of this list. Status as of October 15, 2026:
- Paramount Skydance and Warner Bros. Discovery (closed October 6, 2026, about $110billion). Netflix had agreed in December 2025 to buy the Warner Bros. studio and streaming business; Paramount's $31 per share cash bid was declared superior in February 2026 and Netflix declined to raise. WBD shareholders received $31.02 per share in cash and the combined company was renamed Skydance (NYSE: SKYD). It will enter the ranked list once the GAAP purchase price is filed.
- SpaceX and xAI (February 2026, $250 billion), then SpaceX and Cursor (closed August14, 2026, $60 billion). SpaceX acquired xAI in an all-stock deal reported at $250 billion, then completed a $60 billion all-stock purchase of the AI coding company Cursor on August 14, 2026. Both are separate from xAI's March 2025 acquisition of X, which valued that combined entity at roughly$113 billion.
- Electronic Arts take-private (closed August 4, 2026, $55 billion). PIF, Silver Lake and Affinity Partners paid $210 in cash per share and delisted EA from Nasdaq, the largest all-cash sponsor take-private on record.
- UnionPacific and Norfolk Southern (announced July 2025, $85 billion enterprise value).$320 per share in cash and stock. The Surface Transportation Board rejected the first application as incomplete in January 2026, accepted the revised application on May 28, 2026 and on September 18, 2026 denied motions to dismiss it. Opening comments are due November 18, 2026 and responses by February 16, 2027, so a decision before mid-2027 is unlikely.
- Kimberly-Clarkand Kenvue (announced November 2025, $48.7 billion enterprise value).$3.50 in cash plus 0.14625 Kimberly-Clark shares per Kenvue share. Shareholders of both companies approved it on January 29, 2026 and the European Commission cleared it on October 13, 2026 subject to the sale of Kimberly-Clark's European feminine care brands. Closing is expected in the second half of 2026.
- Anglo American and Teck (announced September 2025, all-share merger of equals, about$54 billion combined). Every regulator except China's SAMR has cleared it; as of October 2, 2026 SAMR was seeking copper supply commitments and the companies expect to close by March 2027. As a merger of equals with no purchase price it will join the structural combinations group, not the ranked list.
Related: Recent M&A Deals and 8 Biggest M&A Deals in History (so far) and 8 Biggest Upcoming M&A Deals in 2026
Biggest mergers and acquisitions examples list
You might assume that bigger M&A deals are more likely to fail, or at least disappoint shareholders. But the reality isn't as clear-cut. While some of the largest mergers and acquisitions in history have stumbled, many others have achieved remarkable strategic and financial success.
True, there have been deals that haven't quite lived up to expectations for one reason or another. But many have done precisely what they set out to do: gain increased market share, achieve synergies, and fuel growth.
With all of this in mind, here are 29 of the largest acquisitions of all time, ranked by inflation-adjusted value, followed by 11 famous combinations that are usually ranked alongside them but were never acquisitions.
Additionally, there are a number of mergers that are often referred to as acquisitions:
"When we bought Charles River, they were very successful, but they were very creative - that's not equivalent to what a banking structure is. We took steps to make sure we didn't destroy the culture and creativity. They kept their old email, still had that identity as a division of State Street. We maintain their facility. That brand name is still there."
Speaker: Keith Crawford, Global Head of Corporate Development, State Street Corporation
Shared at The Buyer-Led M&A™ Summit (watch the entire summit for free here)
Top 5 M&A Failures
If the deals above show what success looks like at scale, these five examples show how quickly value can be destroyed when strategic, cultural, or due-diligence issues are missed:
- AOL and Time Warner (2000, $182B). Goodwill writedown of $99B in 2002, the largest in corporate history at the time. Unwound in 2009.
- Daimler-Benz and Chrysler (1998, $36B). Cultural mismatch led to operating independence; sold to Cerberus Capital Management for $7.4B in 2007.
- HP and Autonomy (2011, $11.1B). HP took an $8.8B impairment charge in November 2012, most of it attributed to accounting improprieties at Autonomy.
- Sprint and Nextel (2005, $35B). Two incompatible network technologies; Sprint recorded a goodwill impairment of $29.7 billion for 2007, reported in February 2008.
- Bayer and Monsanto (2018, $63B). Bayer's glyphosate provision stood at EUR 9.6 billion (about $11.3 billion) at the end of 2025; a $7.25 billion class settlement proposed in February 2026 and a June 2026 Supreme Court win in Durnell have reduced, not removed, the exposure.
- continues.
- and continues to weigh on the combined company.
For a deeper analysis of why these and other deals went wrong, see our companion post on The Biggest M&A Failures of All Time.
Fast-Growing Arenas Reshaping M&A
One large shift we're seeing dealmakers make: increasing their bets on high-growth "arena" industries for future value. McKinsey & Company defines the 18 fastest-growing industries as "arena" industries characterized by technology innovation, new business models, and new and expanding markets. McKinsey Global Institute estimates these arenas could grow from 4% of global GDP today to 10 to 16% by 2040 (October 2024).
Dealmakers are already shifting toward these sectors. In Bain's M&A Report 2026, 60% of deals valued above $1 billion in the first nine months of 2025 were scope deals, bought for growth or capability rather than scale, with the rebound in technology deal volume the clearest sign. Corporate buyers and financial sponsors are both paying up for growth assets, and we expect that to continue while the arenas McKinsey identifies compound faster than the economy. Deal sponsors are also willing to pay premiums to win bets in these industries: buyouts in arena industries are trading at 27.1x EV/EBITDA on average versus 16.5x EV/EBITDA for non-arena industries. While the majority of these high-growth arenas fall within the digital economy, several health care innovations are also among this group.
Corporate and financial sponsors are keen to invest. Not only are private equity investors increasing their share of deal value to companies in arena industries (24% today vs. 18% five years ago), but corporate dealmakers in traditional industries also now account for 33% of all deal value to companies in arenas, up from 24% five years ago. Given the strong growth and profitability prospects in these sectors, we expect them to continue investing at this pace.
How M&A patterns differ by sector
Energy. Oil and gas companies consolidated in record numbers in 2025 to capture scale, cut unit costs and integrate value chains (Bain M&A Report 2026). Examples on this list: Chevron and Hess, ExxonMobil and Pioneer, Saudi Aramco and SABIC.
Tech. Buyers turned to scope deals in 2025: 60% of deals above $1 billion in the first nine months of the year were scope rather than scale, with the rebound in tech deal volume the clearest evidence (Bain). Examples: Microsoft and Activision Blizzard, Broadcom and VMware.
Pharma. Executives used M&A to define the parts of the value chain they truly needed to own (Bain). Examples: Bristol-Myers Squibb and Celgene, AbbVie and Allergan, Pfizer and Warner-Lambert.
Media. Two decades of cycles: AOL and Time Warner was unwound in 2009, Disney and Fox consolidated content IP, Discovery and Warner Media formed Warner Bros. Discovery in 2022 and Paramount Skydance bought that company in October 2026.
Lessons from Successful and Failed Mergers and Acquisitions
Whether the deal was a success or a failure, there are lessons to be learned. Here are the three that recur most often across the 40 transactions on this list.
Never underestimate the power of culture
Culture has historically been one of the least considered aspects of any merger and acquisition. All that seemed to matter in every merger and acquisition deal was money. Fast forward to today, and dealmakers seem to have woken up to the significance of cultural integration.
If you aren't convinced that culture plays a big role in mergers and acquisitions, consider what happened when Daimler-Benz merged with Chrysler on May 7, 1998 in a $36 billion deal.
Daimler was aggressive when it came to integrating with Chrysler. Chrysler, on the other hand, did not like being told what to do. The two companies never saw eye to eye and pretty much operated independently of each other. Needless to say, it was a disaster. Daimler-Benz was then forced to sell Chrysler to another company named Cerberus Capital Management.
Don't take due diligence for granted
Failed M&A deals share a single most-common cause: due-diligence gaps that allowed material misrepresentations to survive into the post-close environment. One misstep can create massive headaches that could potentially ruin your company.
HP learned this the hard way after its $11.1 billion acquisition of Autonomy in October 2011, which led to an $8.8 billion writedown one year later. HP wanted their company to start transitioning from producing computers and printers to a software company that provides services. But things went south once the deal was sealed. An investigation revealed that Autonomy had been manipulating its finances by offloading hardware below cost and mislabeling the revenue as software licensing.
Plan for integration early
The integration management officeshould be launched at announcement, not after close. The months between signingand closing are the only window in which synergy assumptions can still betested against the target's real numbers.
Neglecting to plan for integration is probably the worst thing that any M&A practitioner can do. Integration is where the value is created. Take, for example, the Sprint and Nextel Communications merger.
In 2005, Sprint and Nextel announced a $35 billion all-stock merger to become the third-largest telecommunications company. They wanted to leverage each other's customer bases to then sell additional products to those groups.
Since the company neglected to plan for integration, they were ill-equipped for what would happen post close. The two networks used completely different technologies and did not overlap. The company also suffered from massive market share losses due to conflicting marketing strategies. This allowed competitors to lure away unhappy customers.
Frequently Asked Questions
What is the main purpose of mergers and acquisitions?
The fundamental aim of mergers and acquisitions is to enhance the market share of a business, extend the product line of the business, or reduce the costs of the business. Mergers and acquisitions can also happen when a business seeks to become competitive or create value for shareholders.
Is an acquisition a takeover?
A takeover is one type of acquisition, so an acquisition is not always a takeover. In an acquisition the buyer purchases control of the target, usually in a deal negotiated with and recommended by the target's board. A takeover is an acquisition made by going directly to the target's shareholders without the board's support, which makes it hostile. Vodafone's acquisition of Mannesmann began as a hostile takeover in 1999 and completed in 2000 at $202.8 billion including debt once the boards agreed terms.
What is the biggest concern people have about mergers?
The biggest concern people have about mergers is job losses. Most merger models count cost synergies from removing duplicated roles in finance, IT, sales and management, so employees expect layoffs. Culture clash and the loss of key people are the next concerns: Daimler-Benz and Chrysler (1998, $36 billion) never integrated and Chrysler was sold to Cerberus in 2007 for $7.4 billion. Customers worry about price and product changes, which is why Broadcom's 2023 purchase of VMware is rated mixed on this list.
What happens when two companies merge?
When two companies merge, they combine into one legal entity: shareholders of both receive shares in the combined company, the boards and management teams are consolidated and operations, systems and brands are integrated over one to three years. Overlapping functions are cut to capture synergies. Linde and Praxair (2018) merged into a new holding company on a roughly 50/50 share exchange. Dow and DuPont (2017) merged and then split into three companies in 2019.
What is the merger paradox?
The merger paradox can be described as a situation of unrealized expectations. It is a fact that a merger is always accompanied by a certain level of expectations. However, it has been noted that a merger does not always come to pass as expected but instead leads to a situation of inefficiency.
What are two motives behind mergers and acquisitions?
One of the most common motives behind mergers and acquisitions is to create a combined company that is more valuable than the value of the two companies before the merger or acquisition (greater than the sum of its parts). Mergers and acquisitions are also motivated by market expansion opportunities, which allow a company to enter new geographic regions or product markets quickly.
What is an example of a successful acquisition?
An example of a successful acquisition is Disney's purchase of Pixar in 2006 for $7.4 billion. Disney kept Pixar's creative leadership and Emeryville campus, and the first three Pixar films released after the deal (WALL-E, Up and Toy Story 3) grossed about $2.3 billion worldwide. A second example of a successful acquisition is Google's 2005 purchase of Android for a reported $50 million: Android now runs on about 69% of the world's smartphones, the highest return on any acquisition on record.
What is the greatest acquisition of all time?
The greatest acquisition of all time depends on the measure. By inflation-adjusted value, the greatest acquisition is Vodafone's hostile purchase of Mannesmann, completed in 2000 at $202.8 billion including debt (about $388.6 billion in 2026 dollars). By nominal value it is SpaceX's $250 billion acquisition of xAI in February 2026. By return on the price paid, Google's reported $50 million purchase of Android in 2005 is the greatest acquisition of all time.
What is a real life example of an acquisition?
A real life example of an acquisition is Microsoft's purchase of Activision Blizzard. Microsoft announced the acquisition in January 2022 at $68.7 billion, won approval from the FTC, the European Commission and the UK CMA, and closed it on October 13, 2023 at a GAAP purchase price of $75.4 billion, the largest gaming acquisition on record. A 2026 real life example is Paramount Skydance's acquisition of Warner Bros. Discovery for about $110 billion, completed October 6, 2026.
Final thoughts
All in all, it's hard to argue which merger or acquisition has been the most successful, because sometimes it takes years for the value and potential of a merger or acquisition to formulate.
However, it's been observed that the best mergers and acquisitions (just like some that have yet to be made in terms of M&A deals) are those that take into consideration best practices in communication, strategic goal/deal thesis, and integration planning.
Technology and tools may also be used in making a deal successful.
The DealRoom M&A Platform has been developed to assist M&A teams in effectively managing complex M&A deals. The DealRoom M&A Platform is a unified platform that has been specifically designed to meet the requirements of M&A teams by providing a streamlined solution to effectively manage all aspects of M&A deals, including M&A pipeline management, the entire due diligence process, and post-merger integration.