







The largest leveraged buyout in history is now Electronic Arts: PIF, Silver Lake and Affinity Partners closed the $55 billion take-private on August 4, 2026, with $20 billion of debt committed by JPMorgan. It overtook the $45 billion TXU buyout of 2007, which ended in the biggest LBO bankruptcy ever. Measured including debt, the largest leveraged buyouts in history are EA ($55B), TXU ($45B), Medline ($34B), HCA ($33B) and RJR Nabisco ($31B), then First Data, Heinz, Alltel and Blackstone's Hilton deal, the most profitable LBO on record. In my decade as an M&A advisor before founding DealRoom in 2012, these were the reference points for every buyout model I built.
This is an interactive table we built that you can filter to dig deeper into LBOs:
Or use our interactive LBO return calculator to determine what the return for an LBO likely was, and how it stacks up:
10 Largest Leveraged Buyouts (LBOs) in History
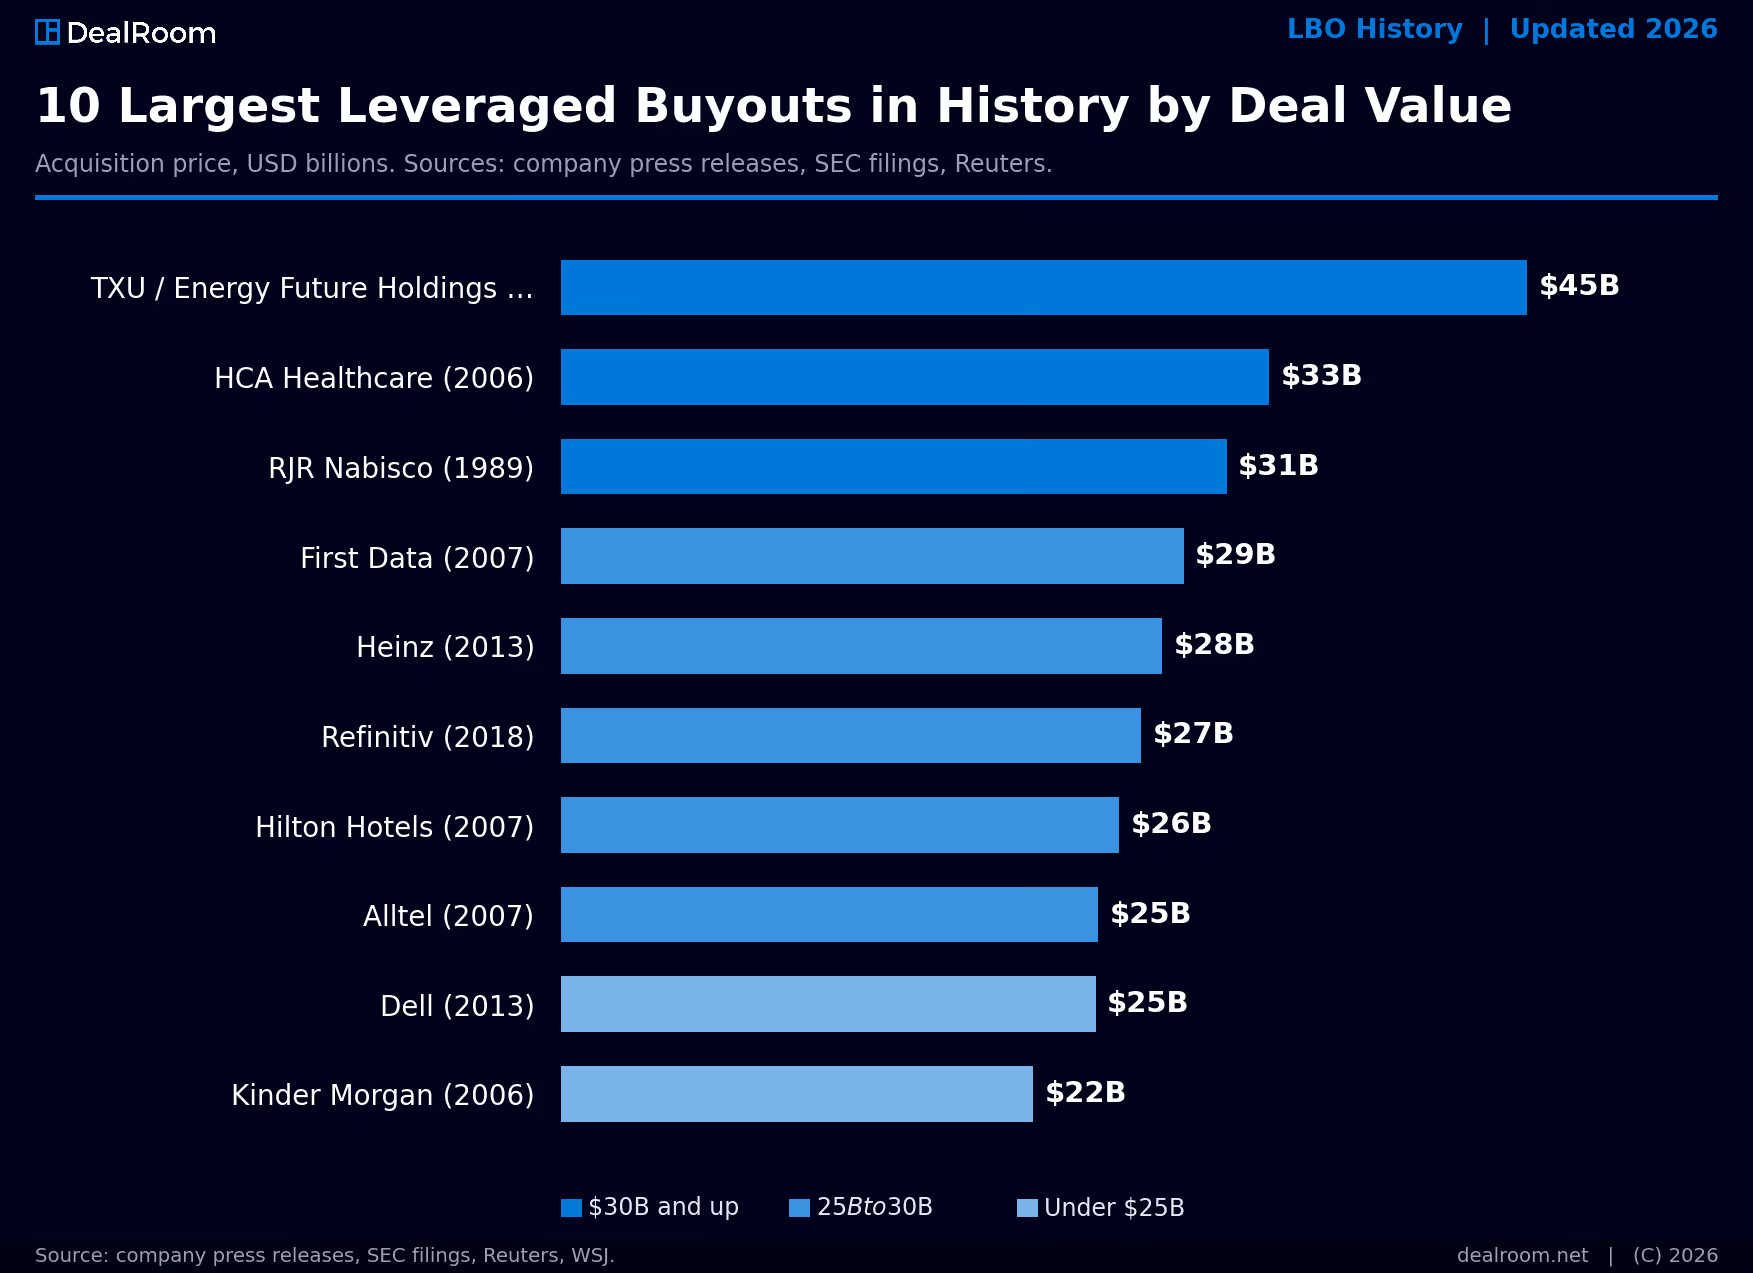
Values are the total price including assumed debt, which is how the sponsors and the acquired companies reported them.
1. ElectronicArts (2026): $55 billion
2. TXU (now Energy Future Holdings) (2007): $45 billion
3. Medline(2021): $34 billion
4. HCAHealthcare (2006): $33 billion
5. RJRNabisco (1989): $31 billion ($25 billion equity value)
6. FirstData (2007): $29 billion
7. Heinz(2013): $28 billion
8. Alltel(2007): $27.5 billion
9. HiltonHotels (2007): $26 billion
10. Dell(2013): $24.9 billion
Just outside the top ten: Kinder Morgan (2006, $22 billion) and Refinitiv (2018, $20 billion valuation for a 55% stake), both covered below.
1. Electronic Arts (2026): $55 billion
On August 4, 2026, a consortium of Saudi Arabia's Public Investment Fund (PIF), Silver Lake and Affinity Partners completed the acquisition of Electronic Arts at $210 per share in cash, and EA's stock was delisted from Nasdaq. The deal, announced on September 29, 2025 at an enterprise value of about $55 billion, was funded with roughly $36 billion of equity(including PIF's rolled-over stake) and $20 billion of debt committed by JPMorgan Chase, $18 billion of it drawn at close. It is the largest leveraged buyout in history and, by EA's own description, the largest all-cash sponsor take-private ever, ahead of the $45 billion TXU deal of 2007.Outcome: too early to call. The thesis rests on EA's sports franchises and live-services revenue carrying about $20 billion of debt at 2026 interest rates, with far more equity in the structure than the 2007 mega-deals used. Interesting Fact: PIF had been a minority EA shareholder for more than five years before leading the buyout, and the deal closed roughly ten months after signing.
2. TXU (now Energy Future Holdings) (2007): $45 billion
In 2007, KKR,TPG and Goldman Sachs Capital Partners acquired TXU (later renamed Energy Future Holdings) in a $45 billion leveraged buyout including debt, the largest LBO in history until the $55 billion Electronic Arts take-private closed in August 2026.
The deal failed, with EFH filing for Chapter 11 bankruptcy in 2014 amid collapsing natural gas prices and an unsustainable debt load that wiped out the entire $8 billion equity check.
This Leveraged Buyout deal was led by KKR, TPG Capital, and Goldman Sachs. This deal involved a Leveraged Buyout of a Texas-based energy company by these private equity giants. It involved a huge amount of debt and relied on high cash flow generated by the target company. However, owing to a financial crisis and a fall in gas prices, the company could not pay its debt and filed for bankruptcy.

Interesting Fact: Despite being one of the biggest LBOs in the world, the TXU LBO ended in bankruptcy because of the unexpected economic downturns.
"The TXU deal underscores the importance of anticipating market shifts and having robust exit strategies in place."
- Financial Analyst
3. Medline(2021): $34 billion
In June 2021, Blackstone, Carlyle and Hellman &Friedman, with GIC as a co-investor, agreed to buy a majority stake in Medline, the family-owned medical supplies maker, in a deal reported at up to $34 billion including debt with a $17billion equity cheque, the largest LBO since the 2007 cycle. The deal closed in late 2021. Outcome: on track. Medline returned to Nasdaq on December 17, 2025 in an IPO that raised more than $7 billion, the largest healthcare IPO on record and the largest PE-backed IPO ever, with the sponsors retaining large stakes. Interesting Fact: Medline was still majority-owned and run by the founding Mills family at the time of the buyout, which kept management in place through the hold.
4. HCA Healthcare (2006): $33 billion
In 2006, Bain Capital, KKR and Merrill Lynch Global Private Equity acquired HCA Healthcare in a $33 billion leveraged buyout, including about $11.7billion of assumed or repaid debt, at $51 per share.
The deal succeeded, with HCA returning to public markets via a 2011 IPO and the sponsors generating an estimated 3-4x return on their equity over the hold period.
HCA Healthcare was acquired by KKR and Bain Capital through an LBO. It was a management buyout, which means the management of the company played a significant role in the LBO. The large amount of debt was supported by the cash flows of the company. Despite the high interest rates, the constant cash flows helped the company utilize the borrowed funds in the most efficient manner, thus making the LBO a huge success.

Interesting Fact: The success of HCA Healthcare in paying back the debts despite the high interest rates highlights the importance of cash flows in LBOs.
"HCA Healthcare's steady cash flow proved to be the lifeblood that sustained the company through the challenges of heavy debt."
- Industry Expert
5. RJR Nabisco (1989): $31 billion
In 1989, KKR completed the acquisition of RJR Nabisco at $109 per share, a $25 billion equity value and about $31 billion including assumed debt, the largest LBO in history at the time and the subject of the book "Barbarians at the Gate."
The deal had a mixed outcome, with KKR breaking up the company over the following decade and the cigarette / food split ultimately delivering modest returns relative to the headline price.
The LBO of RJR Nabisco by KKR is one of the most famous LBOs in the world, as it’s often cited as an example of the working of an LBO. It was a hostile takeover, where the price paid was also quite high, funded by debts. The assets of the target company were utilized to back the debts. Despite the high interest rates, the LBO model proved to be a success in the initial years, but the performance of the company was not satisfactory because of the large debts.

Interesting Fact: The RJ Nabisco deal is included in the book "Barbarians at the Gate," providing a detailed and interesting account of the deal and its complexities.
"The RJR Nabisco deal remains a cautionary tale of the perils of over-leveraging and underestimating market dynamics."
- Financial Historian
6. First Data (2007): $29 billion
In 2007, KKR acquired First Data in a $29 billion leveraged buyout. The deal had a mixed outcome - First Data spent more than a decade carrying its LBO debt load before re-IPOing in 2015 and was ultimately sold to Fiserv in 2019 for approximately $22 billion in stock.
First Data was bought by KKR, where the company’s stable cash flows from processing transactions were used for the financial transaction. The financial deal included a significant amount of debt, and the company aimed to maintain a high level of returns with consistent revenue generation. The financial crisis, however, posed a threat, and the company still managed to go public again, providing a successful exit for the PE companies involved.

Interesting Fact: First Data’s ability to withstand the financial crisis and again go public is a clear indicator of the adaptability of companies in the face of adversity.
"First Data's journey from private to public again exemplifies the cyclical nature of financial markets and the resilience of well-managed firms."
- Market Analyst
7. Heinz (2013): $28 billion
In 2013, Berkshire Hathaway and 3G Capital acquired H.J. Heinz in a $28 billion leveraged buyout. The deal succeeded - Heinz was merged with Kraft Foods Group in 2015 to form Kraft Heinz (KHC), one of the largest food companies in the world, with Berkshire and 3G retaining major stakes through the public-market combination.
Berkshire Hathaway and 3G Capital bought Heinz, a public company, and the deal included borrowed funds and equity finance. The strong company brand and stable cash flows were key factors in raising funds for the deal. The investment expertise of the acquiring company in managing high interest rates and a significant amount of debt led to a successful public issue of the combined company.

Interesting Fact: Warren Buffett's involvement in the Heinz acquisition gave an additional layer of prestige and attention to the deal.
"The Heinz deal, with Warren Buffett at the helm, solidified the merger as a beacon of stability and profitability in the eyes of investors."
- Business Journalist
8. Refinitiv (2018): $27 billion
In 2018,Blackstone (in consortium with Canada Pension Plan Investment Board and GIC) acquired a 55% stake in Thomson Reuters' Financial & Risk business, renamed Refinitiv, in a leveraged buyout that valued the business at $20 billion when it closed on October 1, 2018.
The deal succeeded - Refinitiv was sold to the London Stock Exchange Group in 2021 for $27 billion in stock, generating a multi-billion-dollar gain for Blackstone in roughly three years.
Blackstone completed the acquisition of Refinitiv using its consistent cash flow and essential financial data service. The acquisition financing included a mix of debt and equity. High interest costs were managed through Refinitiv's robust revenue streams. In this LBO deal, Blackstone took advantage of the valuation of the target company in the financial sector.

Interesting Fact: The acquisition of Refinitiv was one of the biggest deals in the financial sector.
"Refinitiv's acquisition highlighted the increasing importance of financial data and analytics in shaping investment decisions and market strategies."
- Financial Analyst
9. Hilton Hotels (2007): $26 billion
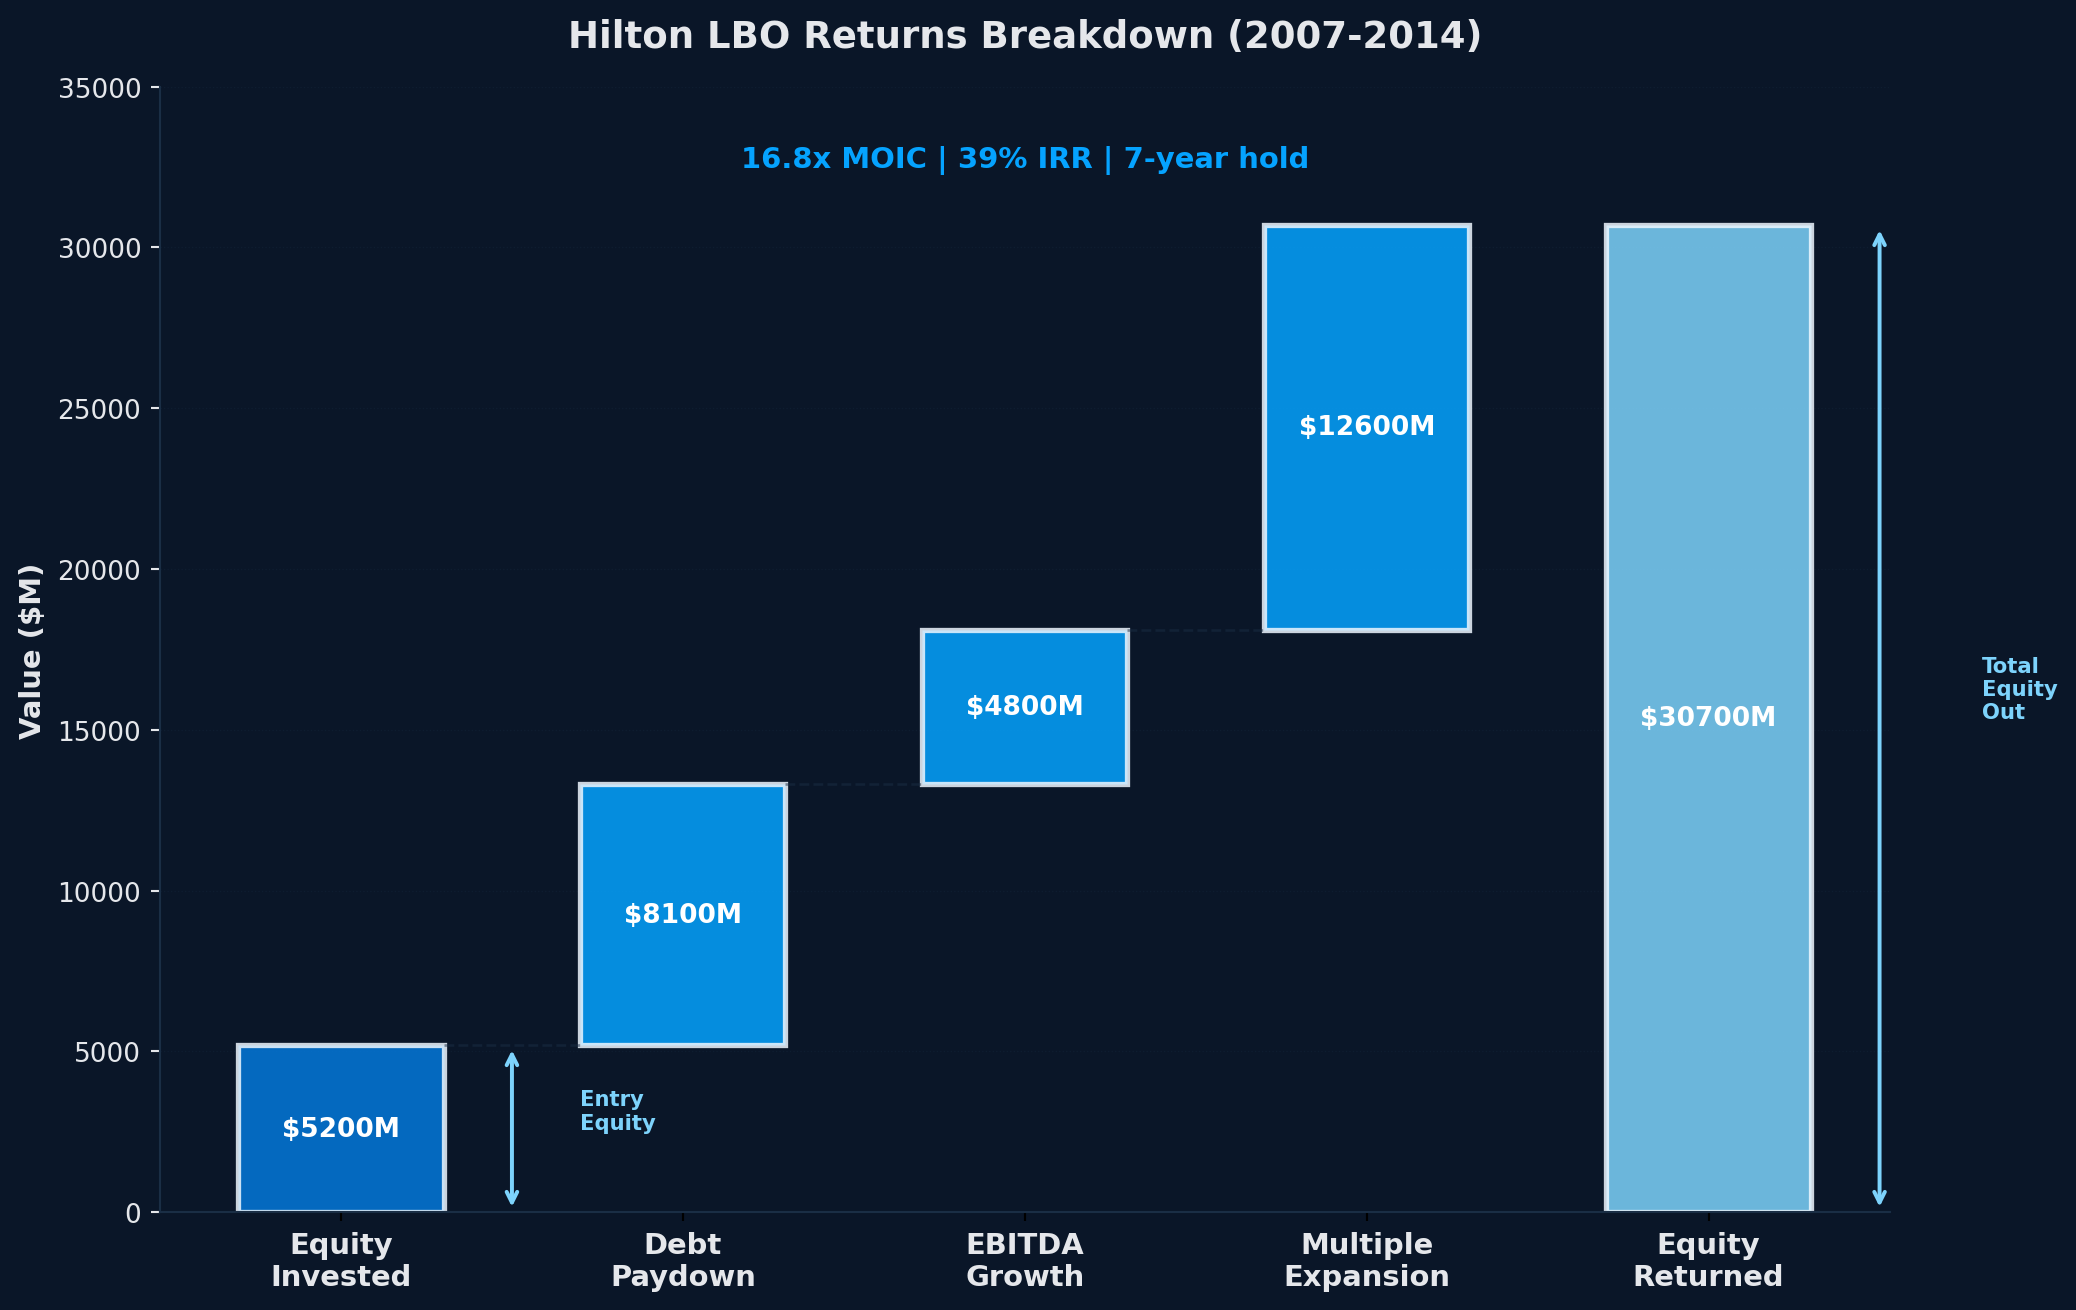
In 2007, Blackstone acquired Hilton Hotels in a $26 billion leveraged buyout. The deal succeeded spectacularly - Hilton returned to public markets via a 2013 IPO and Blackstone's exits over the following years generated approximately $14 billion in profit, making it one of the most profitable PE deals in history.
Blackstone acquired Hilton Hotels just before the financial crisis. Despite the economic crisis, Hilton's consistent cash flow and brand value helped service its debt obligations. In this acquisition deal, Blackstone borrowed a large amount of money. Operational improvements were implemented to increase the rate of return on investment. Finally, Hilton was taken public again, showing a successful exit strategy.

Interesting Fact: Hilton Hotels, which was acquired just before the financial crisis, has managed to come out of the turbulent times, thus proving the viability of the business model.
"Hilton's ability to weather the storm and emerge stronger underscores the enduring value of brand reputation and operational excellence."
- Hospitality Expert
10. Alltel (2007): $25 billion
In 2007, TPG Capital and Goldman Sachs Capital Partners acquired Alltel at $71.50 per share, a $27.5 billion leveraged buyout including debt.
The deal succeeded - the sponsors flipped Alltel to Verizon for approximately $28.1 billion just one year later, in mid-2008, generating one of the fastest LBO exits in industry history.
TPG Capital and Goldman Sachs acquired Alltel, a telecommunication company, when mobile technology was in transition. The acquisition was financed using Alltel's cash flows and projected growth. Within a year, Alltel was sold to Verizon, providing a lucrative exit for the private equity firms.

Interesting Fact: Alltel's acquisition by Verizon was a quick process, showing how dynamic the telecommunication sector is.
"The Alltel deal epitomizes the speed and agility demanded in an industry characterized by rapid technological advancements and fierce competition."
- Telecom Analyst
11. Dell (2013): $24.9 billion
In 2013, Silver Lake Partners and founder Michael Dell acquired Dell Inc. in a $24.9 billion leveraged buyout, structured as a management-led take-private. The deal succeeded - Dell completed a transformational acquisition of EMC for $67 billion in 2016, returned to public markets in 2018, and the sponsors generated multi-billion-dollar returns on the take-private bet.
Michael Dell took his company private in partnership with Silver Lake Partners. He wanted to restructure his company without interference from external factors. It was a management buyout involving a lot of debt using the company's assets and projected growth. He wanted to restructure and increase the company's valuation before seeking a public listing again.

Interesting Fact: Michael Dell's decision to take his company private is a move in the right direction for restructuring and repositioning his company for long-term growth.
"Michael Dell's bold move to take the company private was driven by a vision to reinvent Dell for the digital age, free from the constraints of quarterly earnings expectations."
- Tech Industry Insider
12. Kinder Morgan (2006): $22 billion
In 2006,Richard Kinder and Kinder Morgan's senior management, backed by Goldman Sachs Capital Partners, AIG, Carlyle and Riverstone, led a $22 billion leveraged buyout at $107.50 per share, including about $7 billion of assumed debt, taking the energy-infrastructure company private.
The deal succeeded - Kinder Morgan returned to public markets via a 2011 IPO and is now one of the largest midstream-energy operators in North America.
This LBO transaction was led by the company's management and Goldman Sachs, where Kinder Morgan went private. The company raised a huge amount of debt, which was secured by the company's consistent cash flows from its energy infrastructure business. The company faced some problems, but its consistent cash flows helped it to manage its debt and interest repayment obligations.

Interesting Fact: The successful management of debt obligations by Kinder Morgan is a significant fact in the context of LBOs in the energy infrastructure industry.
"Kinder Morgan's ability to thrive amidst the challenges of the energy market reaffirms the resilience of infrastructure investments in the long term."
- Energy Analyst
Most Recent Leveraged Buyouts (2024-2026)
The take-privates below are the largest sponsor-led buyouts closed since 2024 outside the top-ten list, verified against the acquirers' own announcements. Together with Electronic Arts, they mark the return of the mega-LBO: Bain counts 13 buyouts of $10 billion or more in 2025 and global buyout value of $904 billion, up 44%.
1. Endeavor Group: $25 billion (2025, Silver Lake)
Sector: Media and entertainment (WME, IMG, TKO stake) · Country: USA · Outcome: Active
Silver Lake completed the take-private on March 24, 2025 at $27.50 per Class A share, with Mubadala, DFO Management, Lexington Partners, Goldman Sachs Asset Management and CPP Investments as co-investors. Silver Lake puts the combined total enterprise value at $25 billion including TKO, so the figure is not directly comparable to the all-in prices above.
2. Walgreens Boots Alliance: up to $23.7 billion (2025, Sycamore Partners)
Sector: Pharmacy retail · Country: USA · Outcome: Active
Sycamore paid $11.45 per share in cash, a total transaction value of up to $23.7 billion including debt and contingent VillageMD proceeds and closed on August 28, 2025. It is the largest retail take-private since the 2007 cycle and splits the business into separately run US retail, Boots and healthcare units.
3. Hologic: up to $18.3 billion (2026, Blackstone and TPG)
Sector: Medical devices and diagnostics · Country: USA · Outcome: Active
Blackstone and TPG agreed on October 21, 2025 to pay $76 per share in cash plus a contingent value right of up to $3, an enterprise value of up to $18.3 billion, with minority investments from ADIA and GIC and committed debt from Citi, Bank of America, Barclays, RBC and SMBC. The deal closed on April 7, 2026 and Hologic left Nasdaq.
4. Truist Insurance Holdings: $15.5 billion (2024, Stone Point, CD&R and Mubadala)
Sector: Insurance brokerage · Country: USA · Outcome: Active
An investor group led by Stone Point Capital, Clayton, Dubilier & Rice and Mubadala bought the business from Truist at an implied enterprise value of $15.5 billion, about 18x 2023 core EBITDA and closed on May 7, 2024. It was the largest carve-out LBO of 2024.
5. Nord Anglia Education: $14.5 billion (2025, EQT-led consortium)
Sector: Private K-12 schools · Country: UK, global · Outcome: Active
EQT, Neuberger Berman Private Markets, CPP Investments, CF Alba and Dubai Holding completed the acquisition on March 20, 2025 at a $14.5 billion valuation, a continuation-style deal that moved the company from an older EQT fund to a new consortium.
6. Dayforce: $12.3 billion (2026, Thoma Bravo)
Sector: HR and payroll software · Country: USA · Outcome: Active
Thoma Bravo closed the $70 per share take-private on February 4, 2026, valuing Dayforce at about $12.3 billion. The stock was delisted from the NYSE and TSX.
Pending: a consortium led by Global Infrastructure Partners (BlackRock) and EQT, with CalPERS and the Qatar Investment Authority, agreed on March 2, 2026 to take AES private at $15 per share, a $10.7 billion equity value and about $33.4 billion enterprise value including assumed debt, with closing expected in late 2026 or early 2027. If it closes it would rank third on this list by total value.

The Anatomy of a Leveraged Buyout
Every LBO on the list above follows the same four-step structure - what changes is the size of the deal, the source of the debt, and whether the bet pays off. Here's how a leveraged buyout actually works.
Sponsor identifies a target
A private equity firm targets a public or private company with stable cash flow, undervalued assets, or hidden cost-cutting potential. The thesis: financial engineering plus operating improvements will compound returns over a 5-7 year hold.
Capital stack is assembled
The sponsor funds the purchase with roughly 40-50% equity from its own fund and 50-60% debt (sponsors averaged 46% equity in 2025 and a record 51% in 2023, according to PitchBook LCD; the 2007 mega-deals ran at 18-20% equity) - a mix of senior bank loans, high-yield bonds, and mezzanine debt. The debt sits on the target's balance sheet, not the sponsor's.
Operate, deleverage, optimize
During the hold period the new owners use the target's free cash flow to pay down debt while executing on the operating thesis - cost cuts, divestitures, bolt-on M&A, management changes, or geographic expansion. As debt falls, equity value rises.
Exit (or default)
The sponsor exits via re-IPO (Hilton, Dell), strategic sale (Heinz to Kraft), or secondary buyout to another sponsor. When the operating thesis fails or the debt load proves unsustainable, the LBO ends in bankruptcy (TXU, Caesars), wiping out the equity.
The deals above illustrate every possible outcome - from the most profitable PE deal in history (Hilton) to the largest LBO bankruptcy ever (TXU).
How Mega-LBOs Are Financed in 2026 Compared With 2007
Mega-LBOs in2026 are financed with far more equity and less debt than the 2007 vintage: sponsors now fund roughly 45% to 65% of the price with equity and borrow under 5x EBITDA, where the 2007 deals used 18% to 20% equity. The 2006-2008 deals on this list were built on thin equity: KKR, TPG and Goldman Sachs put roughly $8 billion of equity into the $45 billion TXU buyout, under 20% of the price. Blackstone wrote a 20% equity cheque for Hilton. The 2026 record deal is structured differently. Electronic Arts was bought at a $55 billion enterprise value with about $36 billion of equity and $20 billion of debt committed by JPMorgan, so debt covers roughly a third of the price rather than four fifths.
That is the market norm now, not an exception. PitchBook LCD data shows sponsors contributed 46% equity on US syndicated-loan buyouts in 2025, after a record 51% in 2023, against a ten-year average of 41% through 2021. Debt multiples on large buyouts fell from nearly 6x EBITDA in 2022 to 4.8x in 2023 and have stayed under 5x since.
2007 vs 2026: How Mega-LBOs Were Financed
Equity share and debt for two landmark 2007 buyouts and the 2026 record deal.
| Deal | Year | Price incl. debt | Equity share | Debt |
|---|---|---|---|---|
| TXU | 2007 | $45B | About 18% | About $37B |
| Hilton | 2007 | $26B | About 20% | About $21B |
| Electronic Arts | 2026 | $55B | About 65% | $20B committed, $18B drawn at close |
Note. Figures are approximate and sourced in the text around this table. dealroom.net
The cost of that debt is also higher than in 2021. SOFR was 3.88% on October 14, 2026 and new-issue spreads for B-minus borrowers averaged 354 basis points in late 2025, so a typical LBO term loan prices near 7.4% all-in; the US leveraged loan index yielded 8.26% at June 30, 2026. Hologic's $18.3billion take-private by Blackstone and TPG used a bank group of Citi, Bank of America, Barclays, RBC and SMBC, a sign the syndicated market is open again for large borrowers. The practical result: today's mega-LBOs carry less leverage risk than the 2007 vintage, but with less debt to pay down their returns depend more on EBITDA growth and exit multiple.
Frequently Asked Questions
What is a Leveraged Buyout?
A Leveraged Buyout is a situation wherein an investor buys a company with borrowed money. The assets and cash flow of the target company are used as collateral for these debts. This is done to increase the returns on equity.
Why do Private Equity Firms perform Leveraged Buyouts?
Private equity firms perform Leveraged Buyouts because they enable these firms to acquire a company with a smaller amount of capital. This is because they can finance a larger percentage of the deal by debt, thus increasing the potential return on investment. Once they acquire a company, they work on improving it and increasing its profits before selling it or going public.
What are some of the most famous Leveraged Buyouts?
Some of theLeveraged Buyouts that can be considered the most famous include:
- Electronic Arts by PIF, Silver Lake and Affinity Partners($55 billion, 2026, the largest LBO ever)
- RJR Nabisco by KKR
- TXU Energy by KKR, TPG Capital and Goldman Sachs
- HCA Healthcare by KKR and Bain Capital
- Hilton Hotels by Blackstone
- Heinz by Berkshire Hathaway and 3G Capital
What are some of the key determinants of a successful Leveraged Buyout?
The key to a successful Leveraged Buyout is good cash flow, proper debt usage, and effective operations. A clear exit strategy through sale or IPO is important too. For instance, Hilton and HCA were successful due to proper cash flow and constant improvements in operations.
What are some reasons why leveraged buyouts fail?
Leveraged buyouts fail when the target's cash flow can no longer cover interest and principal, usually after an earnings shock, a cyclical downturn or a jump in borrowing costs. TXU is the clearest example: the $45 billion 2007 buyout was abet on high natural gas prices, gas prices fell after the shale boom and Energy Future Holdings filed for Chapter 11 in April 2014, wiping out the roughly $8 billion of sponsor equity. Overpaying at the top of a cycle, cyclical revenue and thin interest coverage are the common ingredients.
How do investors make money in leveraged buyouts?
Investors in a leveraged buyout make money in three ways: paying down debt with the company's cash flow so the equity owns more of the business; growing EBITDA through operating improvements and bolt-on acquisitions; and selling at a higher multiple than they paid. Returns are measured as MOIC (money multiple) and IRR. Blackstone's Hilton deal is the benchmark: about $6.5 billion of equity in 2007 became roughly $14 billion of profit by 2018 through a 2013 IPO and later share sales, about 3x the money invested.
What is the role of management in leveraged buyout?
The management plays a key role in Management Buyouts (MBOs), in which management buys out the business with other investors. Management has knowledge about the business and ensures that goals are achieved in line with other investors.
What are some recent examples of leveraged buyouts?
Recent examples of leveraged buyouts include Electronic Arts ($55 billion, PIF, SilverLake and Affinity Partners, closed August 2026), Hologic ($18.3 billion, Blackstone and TPG, closed April 2026), Dayforce ($12.3 billion, Thoma Bravo, closed February 2026), Walgreens Boots Alliance (up to $23.7 billion including debt, Sycamore Partners, closed August 2025), Endeavor ($25 billion, Silver Lake, closed March 2025) and Nord Anglia Education ($14.5 billion, EQT-led consortium, closed March 2025). The $33.4 billion AES take-private by GIP and EQT, announced in March 2026, is still pending.
What lessons can be learned from past Leveraged Buyouts?
The main lessons from past leveraged buyouts are that cash flow stability, entry price and an operating plan decide the outcome, not deal size. HCA and Hilton serviced heavy debt through the 2008 crisis because hospitals and hotels kept generating cash; TXU, a bet on natural gas prices, went bankrupt in 2014. RJR Nabisco, won in a bidding war, returned little. The market has absorbed these lessons: sponsors contributed 46% equity on US buyouts in 2025 and a record 51%in 2023, against a ten-year average of 41% through 2021, according to PitchBook LCD.
How do Leveraged Buyouts impact employees and operations?
A leveraged buyout changes how a company is run because debt must now be serviced from operating cash flow. Employees typically see a new board, a 100-day plan, tighter capital spending and cost reviews. Common operational changes a remanagement replacement, divestitures of non-core units, bolt-on acquisitions and, in cost-led deals, layoffs. The effect depends on the sponsor's thesis: Hilton expanded under Blackstone and re-listed in 2013, while the 2022 Citrix and TIBCO buyouts were followed by restructuring at the merged Cloud Software Group. Management equity plans usually align senior staff with the sponsor's exit.