





The top venture capital firms by assets under management in 2026 are Andreessen Horowitz ($106.5 billion), Insight Partners ($92.2 billion), Sequoia Capital($82.2 billion) and Tiger Global ($78.0 billion), per each firm's latest SEC Form ADV ,and the 18 largest VC firms ranked below manage a combined $828 billion. Their portfolios are where the biggest exits now happen: acquisitions of US VC-backed companies reached a decade-high $465.3 billion in the first nine months of2026, according to the PitchBook-NVCA Venture Monitor, led by SpaceX's $60 billion purchase of Cursor. This guide covers each firm's AUM, stage focus and M&A exit record, the biggest acquisitions from these portfolios and what buyers should know before acquiring a VC-backed startup.
I’ve worked on the buy side my entire career. First as an M&A advisor, now developing software for deal teams. The divide between venture and M&A continues to blur. The companies featured on these firms’ fund factsheets are the same companies appearing in our customers’ deal pipelines.
The 18 largest VC firms at a glance
M&A is now the default exit for VC-backed companies
Exit math is skewed. PitchBook and NVCA counted 1,029 acquisitions of US VC-backed companies worth $140.7 billion in 2025, against 48 public listings worth $116.7 billion (Venture Monitor Q4 2025). Those full-year totals have since been revised: as of the Q3 2026 edition, 2025 exits stand at $274.5 billion across 1,580 transactions. Acquisitions made up roughly 96% of US VC-backed exits that were either an acquisition or an IPO (1,029 of 1,077) and about 63% of all exits once buyouts and other routes are counted. Realistically the liquidity option for any given portfolio company is a sale not a listing
The same is true at the top of the market. Cisco closed its $3.7 billion deal for AppDynamics two days before the company was scheduled to price its IPO. SAP followed suit with Qualtrics, shelling out $8 billion in cash days before its target’s anticipated IPO. Wiz rejected a $23 billion offer from Google in 2024 only to accept $32 billion a year later. Bottom line for buyers: Don't let a credible IPO path scare you away from a VC-backed target. It's often the catalyst for a decision.
The biggest M&A exits from these portfolios
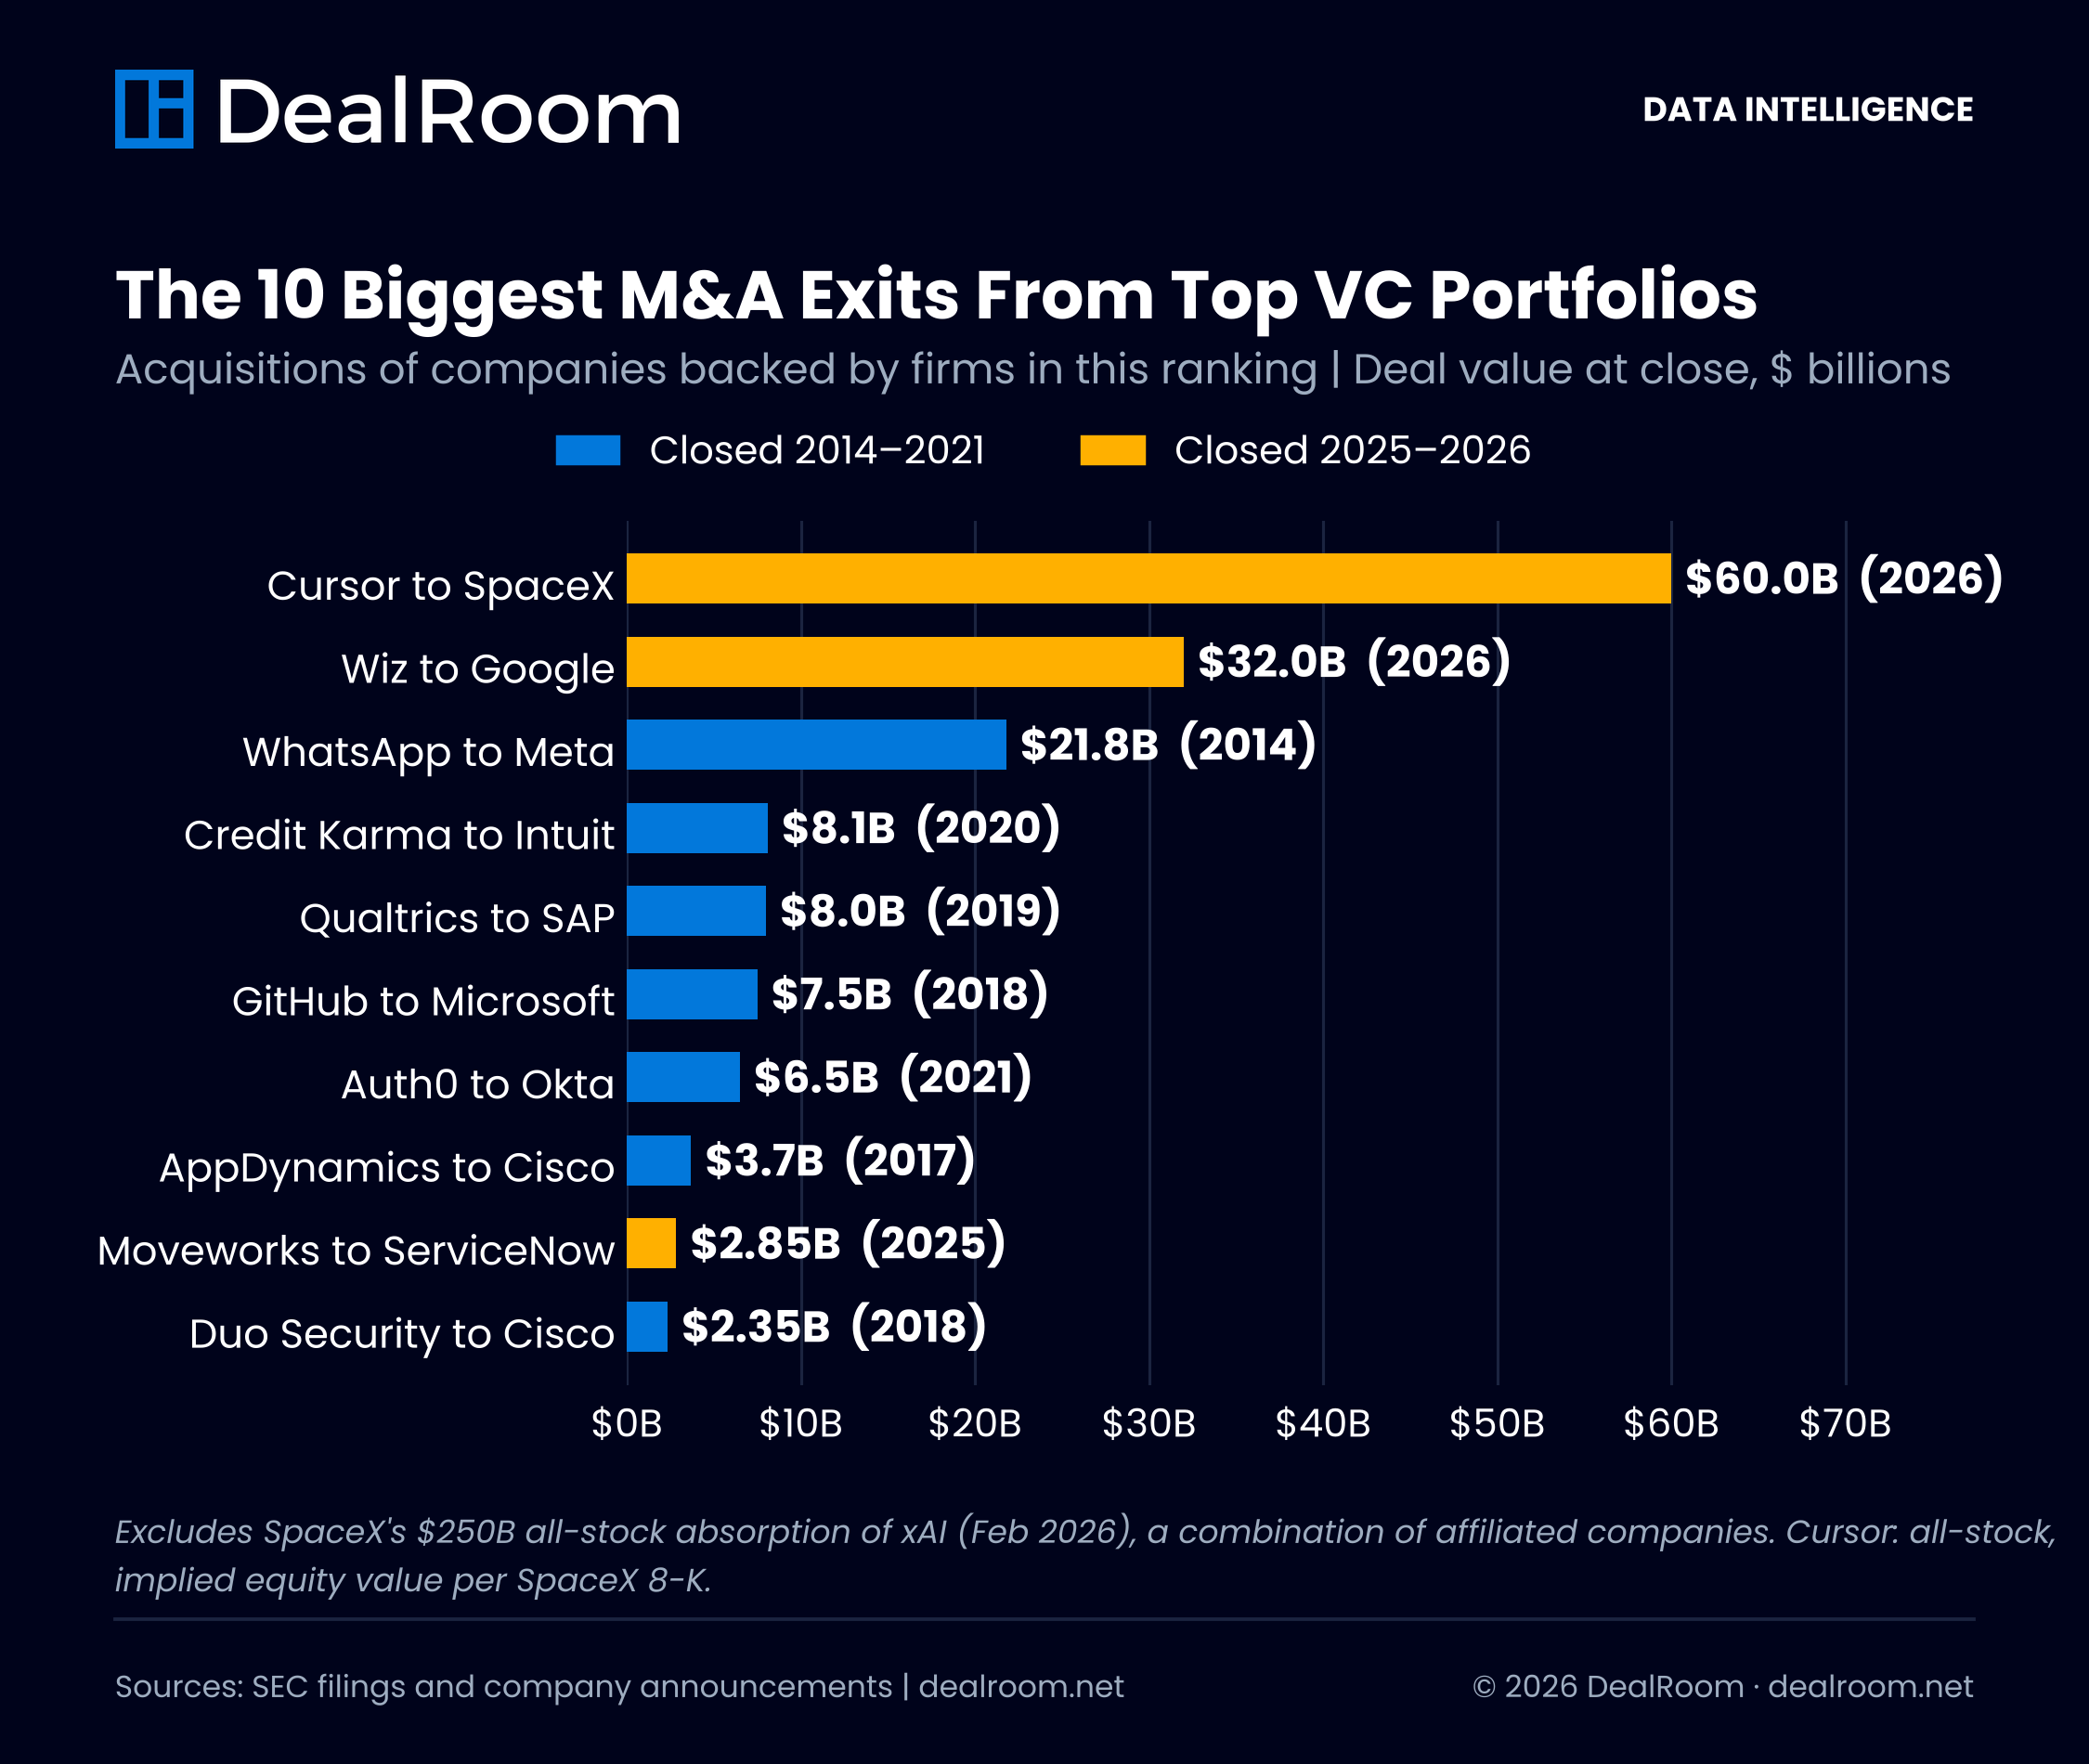
The largest exits of VC-backed companies are almost exclusively from these portfolios. SpaceX's $60billion all-stock purchase of Cursor, closed August 14, 2026, is the largest acquisition of a venture-backed company by an outside buyer; PitchBook ranks it second only to SpaceX's $250billion absorption of xAI in February 2026, a combination of two Musk companies. Google's $32 billion all-cash acquisition of Wiz remains the largest cash exit.
All deals below were VC-backed at time of exit and had at least one investor from this list on the cap table.
Firm profiles: AUM, focus and exit behavior
1. Andreessen Horowitz (a16z)
$106.5B AUM | Menlo Park | Founded 2009
a16z runs dedicated funds across consumer, enterprise, fintech, bio and health, crypto, games, American Dynamism and infrastructure. Its holdings include two of the most analyzed technology deals of the past decade: Microsoft's $7.5 billion acquisition of GitHub, and Facebook's acquisition of Instagram announced at$1 billion and worth roughly $715 million by the time it closed each sourced from among the earliest a16z vintages. The firm raised more than $15 billion across six funds in January 2026, expanded its fifth growth fund to $8.5 billion in August 2026 and added a $1.1 billion AI-hardware fund; PitchBook counts $23.8 billion closed through Q3 2026, more than 20% of all US venture capital raised this year. It now states over $100 billion under management. With dozens of late-stage positions, a16z board members sit across the table in a significant share of large technology mergers and acquisitions.
2. Insight Partners
$92.2B AUM | New York | Founded 1995
Insight leads this list by volume as both a software-focused growth investor and an M&A seller. It has invested in more than 900 companies worldwide and seen over 55reach an IPO. Companies in which Insight held a position at sale include and Cylance. For buyers of B2B software, targeting an Insight-backed company usually means audited metrics, a professionalized go-to-market motion, and a board that knows what a clean process looks like. Worth noting the flagship has come down in size: Fund XIII closed at $12.5 billion in January2025, against $20 billion for Fund XII.
3. Sequoia Capital
$82.2B AUM | Menlo Park | Founded 1972
The oldest franchise also has the deepest M&A exit history: WhatsApp, GitHub, Qualtrics and Wiz all had Sequoia on the cap table at exit. Since the 2023breakup into Sequoia (US and Europe), Peak XV (India and Southeast Asia) and HongShan (China), acquirers should treat each entity as its own counterparty with its own portfolio — the figure above covers Sequoia's US and global growth vehicles only. Roelof Botha handed the senior steward role to co-stewards Alfred Lin and Pat Grady in November 2025; their first major raise was a $7 billion expansion fund in April 2026, and in August 2026 Bloomberg reported plans to raise about $10 billion more, the largest raise in the firm's history.
4. Tiger Global Management
$78.0B AUM firm-wide ($41.1B in venture) | New York | Founded 2001
Tiger deployed at a historic pace in 2021, backing roughly 315 startups close to one a day from a $12.7 billion private vehicle. It pulled back sharply in2022 and now runs a far more concentrated, AI-led book; its latest vehicle, PIP17, targeted $2.2 billion in December 2025. Tiger's operating style is famously hands-off, so its positions seldom block a deal. Credit Karma's exit to Intuit (announced at $7.1 billion, $8.1 billion in total consideration at close) and Moveworks' $2.85 billion sale to ServiceNow were both from Tiger-occupied cap tables.
5. Founders Fund
$58.9B AUM | San Francisco | Founded 2005
Peter Thiel's firm runs two parallel fund families the core Founders Fund series and as separately capitalized growth series and raised roughly $10.6 billion into growth vehicles inside twelve months, with Growth III at $4.6 billion in 2025 and Growth IV at $6.0 billion in March 2026, the largest vehicle in its history. Its M&A exits include Oculus VR's $2 billion sale to Facebook, Credit Karma's $8.1 billion exit to Intuit and Postmates' $2.65 billion sale to Uber. SpaceX listed in June 2026 at a record $1.7 trillion valuation, but much of the rest of the portfolio (Anduril, Stripe, OpenAI, Neuralink) is deliberately long-hold, so a buyer approaching a Founders Fund company should expect an investor base comfortable staying private for a long time.
6. Thrive Capital
$50.5B AUM | New York | Founded 2009
Joshua Kushner's firm concentrates capital behind a handful of high-conviction bets each year. Thrive closed Thrive X at $10 billion in February 2026, nearly double the $5 billion-plus Thrive IX it raised in August 2024. Thrive led Cursor's $900 million Series C in June 2025 and held it through SpaceX's $60 billion all-stock purchase in August 2026, co-led the last private funding round for Wiz and held GitHub before it was sold to Microsoft. Shares are tightly held, so a Thrive position is usually large enough to anchor or veto an exit which keeps negotiation to a small number of decision makers.
7. Lightspeed Venture Partners
$50.0B AUM | Menlo Park | Founded 2000
Lightspeed runs two distinct advisory entities: Lightspeed Management Company (US, Europe, Israel) and Lightspeed India Partners (India, Southeast Asia). In 2025 it registered as an investment adviser, lifting the 20% cap on holdings outside traditional startup equity and opening the door to secondaries, public shares and crypto a structural change worth understanding before you negotiate. Lightspeed co-led AppDynamics' Series A and stayed on through Cisco's $3.7billion pre-IPO acquisition, backed Moveworks through its $2.85 billion sale to ServiceNow, and held Wiz through its $32 billion sale to Google. Few firms have exited via strategic transaction more often.
8. Accel
$46.8B AUM | Palo Alto | Founded 1983
Accel's thesis-driven “prepared mind” research approach has fueled enterprise software Series A deals in software infrastructure and dev tools. Accel held Qualtrics at SAP's $8 billion cash deal and was Slack's largest venture holder, at 23.8%,going into its direct listing Salesforce then bought the public company for $27.7 billion. In April 2026 the firm raised roughly $5 billion for Leaders Fund V plus a sidecar. Accel also co-led Cursor's $2.3 billion Series D in November 2025 at a $29.3 billion valuation, nine months before SpaceX bought the company for $60 billion. Accel turns up on both the buy and sell side of enterprise software consolidation.
9. General Catalyst
$45.5B AUM | Cambridge | Founded 2000
GC operates multi-stage practices in health assurance, enterprise defense, AI infrastructure and consumer. It is also the clearest example of a venture firm becoming a strategic acquirer in its own right: HATCo the Health Assurance Transformation Company, a General Catalyst spinout acquired Ohio health system Summa Health for $515 million, closing October 1, 2025. The firm has been in talks to raise roughly $10 billion and has explored a public listing that would make it the first US venture firm to go public. Healthcare corporate development teams will increasingly meet GC as a competing bidder, not just as a seller.
10. Dragoneer Investment Group
$37.0B AUM | San Francisco | Founded 2012
Dragoneer isa public/private hybrid. Alongside concentrated venture funds a seventh closed at $4.3 billion in December 2025, holding roughly 15 companies each it runs a $12 billion evergreen vehicle that can hold both private and public positions, which lets it stay in through a listing. If Dragoneer is on the cap table, assume an IPO-first posture: an acquirer has to beat what the public markets are offering.
11. New Enterprise Associates (NEA)
$35.6B AUM | Menlo Park | Founded 1977
NEA closed $6.2 billion across two funds in January 2023 and is raising NEA 19, targeting roughly $5.5 billion with a first close in December 2025 to January 2026. Firm-wide it cites more than 270 portfolio company IPOs and more than 450M&A exits, and the exit profile is public-market heavy. But because NEA holds large positions in mid-stage healthcare and enterprise businesses, it is one of the most common counterparties in growth-stage carve-out and roll-up discussions.
12. Index Ventures
$25.3B AUM | San Francisco and London | Founded 1996
Index operates from San Francisco and London, with further offices in New York, Geneva and Jersey. It took Wiz from its initial rounds through the $32 billion Google exit and sold Duo Security to Cisco for $2.35 billion. Its presence on both sides of the Atlantic means its portfolio companies are regularly approached by US and European strategic buyers, sometimes inside the same process.
13. Technology Crossover Ventures (TCV)
$22.5B AUM | Menlo Park | Founded 1995
TCV writes $10 million to $500 million equity checks with flexibility on structure, investing in late-stage internet and software businesses. It counts 82 IPOs and80 strategic exits, with Netflix, Spotify and Toast among the public outcomes. The crossover strategy biases toward listings, so TCV-backed targets often come to market only after the public window has closed.
14. Khosla Ventures
$21.7B AUM | Menlo Park | Founded 2004
Vinod Khosla's firm invests in early-stage deep tech, climate tech and AI with long hold periods it was OpenAI's first venture investor, and is targeting roughly $5.5 billion for its next fund, most of it for early-stage AI. Its largest cybersecurity exit is Cylance's $1.4 billion acquisition by BlackBerry, a position BlackBerry later sold on to Arctic Wolf for about $160 million. Because Khosla concentrates on seed deals carrying real science risk, technical diligence outweighs financial diligence on its companies.
15. OrbiMed
$20.6B AUM | New York | Founded 1989
One of the largest healthcare-dedicated investment firms, with roughly $20 billion across venture, public equities and royalty and credit strategies, 500-plus portfolio companies and 130-plus venture-backed IPOs. Large pharma buyers are the common acquirers of its therapeutics and device positions. Thanks to OrbiMed's MD and PhD bench, diligence materials on its portfolio companies typically arrive at banker quality.
16. Bessemer Venture Partners
$20.2B AUM | Redwood City | Founded 1911 (venture practice since 1974)
Bessemer has led deals in vertical SaaS, cloud infrastructure, fintech and healthcare through Series A to C, and publishes the research behind its investment theses. In September 2026 it raised $5.75 billion in new capital, $1.75 billion for seed and early stage and $4 billion for growth.
Auth0's $6.5 billion sale to Okta is its largest strategic exit of the cloud era. Bessemer-backed companies tend to arrive with clean, benchmarked SaaS metrics, which shortens financial diligence.
17. Deerfield Management
$19.1B AUM | New York | Founded 1994
Deerfield is healthcare-only and spans venture, public equities, structured credit and royalties. It exits therapeutics positions predominantly through pharma acquisition or licensing rather than IPO. Its clinical and regulatory expertise shows up in how well curated its data rooms are.
18. Battery Ventures
$15.6B AUM | Boston | Founded 1983
Battery invests across early, growth and buyout stages inside the same sector, currently deploying Battery Ventures XV at $3.25 billion, with more than $16billion raised since inception. It has also done PE-style buyouts of bootstrapped software companies, which makes it both a buyer and a seller. Glassdoor's $1.2 billion sale to Recruit Holdings originated from a Battery Series A.
Where the top VC firms concentrate: AI, cybersecurity, healthcare and defense
Sector focus tells a buyer which of these firms will be across the table. 82.7% of 2026 US VC deal value has gone to AI companies through September, and the two largest 2026 exits on this list, Cursor ($60 billion, SpaceX) and Wiz ($32 billion, Google), were an AI coding tool and a cloud security platform. Healthcare is the other concentration: 12 of the 18 VC-backed IPOs in Q3 2026 were healthcare companies.
For corporate development teams the practical use is sourcing. A cybersecurity target will usually have Index, Sequoia or Insight on the cap table and a board that has run a Wiz-style process. A therapeutics target will usually have OrbiMed or Deerfield and a buyer set dominated by large pharma.
Why corp dev teams watch VC portfolios
VC portfolios are the most qualified target pool in the market: vetted by pros, benchmarked quarterly and optimized to scale. 2025 numbers prove buyers have taken notice. Startups accounted for 38.4% of acquisitions and22.3% of acquisition value in 2025, according to the Venture Monitor. The types of targets being acquired are young teams bought for capabilities, not revenue.
We described this as'transact to transform' in our State of M&A report: firms acquiring to fill adjacent capabilities instead of developing them organically. We also pointed to signals emerging from within the venture market itself: in our 2023–24 State of M&A report, one VCclient told us over a third of the pitch decks they saw were AI-focused ashare that has only grown since. That focus is now evident across these 18 portfolios. It is precisely where buyers motivated by capability are looking.
Three key signals when screening a VC portfolio:
- Fund age. A company sitting in a 2014 vintage fund will soon feel distribution pressure. GPs with a year or two left on their fund are motivated sellers, even if the company's blog posts are all about how independent they are.
- Follow-on behavior. When insiders don't lead a round and a bridge emerges, the board has likely already started strategic options discussions.
- Investor exit profile. A Dragoneer or TCV investor means you’re about to see an IPO. An Insight or Lightspeed investor means management has sold to M&A multiple times previously.
Don’t do this on an ad hoc basis. Our customers automate this exact filtering within DealRoom Pipeline, along with their entire corporate development workflow.
Acquiring a VC-backed company: what buyers need to know
Buying into a venture-backed company is different than buying a founder-owned business in four ways. These differences become apparent during diligence and negotiation.
The preference stack determines who says yes
Proceeds are not distributed pro rata. Liquidation preferences entitle the holders of preferred stock (aka the VC funds) to a contractual minimum before any proceeds go to common stockholders. At certain prices the preferred investors may be made whole while the founders and employees receive little if anything. This kills deals that may have looked attractive based on headline price.
Run the waterfall before you let a price anchor your thinking. The interactive calculator below demonstrates how preference multiples and participation determine who gets what at any given exit value.
Approvals run through the board and the preferred
Financing docs usually need board approval and consent from one or more preferred classes. Many charters have drag-along provisions forcing common holders after thresholds are reached. Map the approval tree during week 1 diligence: don't assume a deal-supportive CEO is worthwhile if two funds have blocking positions.
Diligence is faster, but different
VC backed targets generally come in with clean financials and diligence products created at each financing. Additional focus should be on the cap table itself (option pools, SAFEs, warrants and convertible notes that convert on close), 280G golden parachute exposure, and treatment of unvested equity. See our due diligence guide for the complete request list. The venture capital due diligence checklist is the checklist we provide our customers who are pursuing these exact targets.
The sell side knows the playbook
A board that includes Insight, Sequoia or Lightspeed has seen dozens of exits. These processes are banker-driven, fast-paced and designed to produce competing bids on deadline. Companies who succeed in winning these processes run their own disciplined buy-side M&A process. They don't let the seller's timeline control them.
How these firms run due diligence (and what it means for your timeline)
Venture diligence takes less time than corporate diligence, and the difference matters when you're competing against a follow-on round instead of another bidder. In our experience working with corp dev teams, venture diligence typically runs one to two weeks at seed, three to six at Series A and four to eight at growth stage far inside a strategic acquirer's confirmatory timeline. If a strategic acquirer runs a 12 week process against a 4 week term sheet they will lose by default. There is a reason rigorously compressed diligence is the core value proposition of purpose-built tooling versus email + spreadsheets.

Frequently Asked Questions
What venture capital firm has had the largest M&A exit?
The venture capital firms with the largest M&A exit are Thrive Capital and Accel, both investors in Cursor, which SpaceX bought for $60 billion in stock on August 14, 2026. PitchBook ranks that deal second only to SpaceX's $250 billion absorption of xAI (backed by a16z, Sequoia and Lightspeed) in February 2026, a combination of two Musk companies. Google's $32 billion all-cash purchase of Wiz, backed by Index Ventures, Sequoia, Insight Partners, Lightspeed and Thrive, remains the largest cash exit for a venture-backed company.
Who has the most money in venture capital?
Andreessen Horowitz has the most money in venture capital, with $106.5 billion in regulatory assets under management on its Form ADV for December 31, 2025, and it closed a further $23.8 billion of funds in the first nine months of 2026. Insight Partners is second at $92.2billion, Sequoia Capital third at $82.2 billion (Form ADV filed July 2026) and Tiger Global fourth at $78.0 billion firm-wide, of which $41.1 billion is venture.
Do VC-backed startups exit through IPO or acquisition?
VC-backed startups exit mainly through acquisition, not IPO. PitchBook and NVCA counted 1,029acquisitions of US VC-backed companies in 2025 against 48 public listings, with the two close by value ($140.7 billion against $116.7 billion). The pattern held in 2026: acquisition value hit a decade-high $465.3 billion through September while only 18 VC-backed companies went public in the third quarter. SpaceX's $1.7 trillion listing in Q2 2026 is the one exception that dominates the year's exit value.
How much time do you have to conduct due diligence on a VC backed target?
You have less time to conduct due diligence on a VC-backed target than on a founder-owned business: in our experience with corporate development customers, venture diligence runs about 1 to 2 weeks at seed, 3 to 6 weeks at Series A and 4 to 8 weeks at growth stage, because each financing round leaves a current data room behind. A strategic acquirer's confirmatory diligence typically takes 8 to 12 weeks, so when you compete against a follow-on round rather than another bidder, build the request list before the LOI and compress the timeline.
What is liquidation preference and why does it matter in M&A?
A liquidation preference is the contractual right of preferred stockholders (the VC funds) to receive a set multiple of their investment before common stockholders receive anything. In Cooley's Q2 2026 venture financing data, 95.8% of deals carried a1x preference and 96.4% were non-participating. In M&A the preference decides who actually makes money at a given price, and therefore which investors support or block the deal, so acquirers should model the preference waterfall before making an offer.
How is venture capital different from private equity in M&A?
Venture capital differs from private equity in M&A in three ways: control, hold period and process. A VC firm holds a minority stake in a startup and exits by selling that one position, usually in a trade sale, so the buyer negotiates with a board of several funds, each with its own liquidation preference. A PE firm owns a controlling stake, holds for 4 to 7 years and sells the whole company through a banker-run auction it controls from start to finish. AVC-backed sale involves more parties; a PE-backed sale runs on the seller's timetable.
Methodology
Rankings are based on public information, primarily SEC Form ADV filings, as well as annual firm reports and corroborated data from Bloomberg, Forbes and the Financial Times. Asset sizes reflect total assets under management, only including firms with $10 billion or more in committed venture or growth capital. M&A exit data is compiled from SEC filings as well as announcements from acquirers and other news published via links in the exits table. Exit market data is from the PitchBook-NVCA Venture Monitor, Q4 2025 and Q3 2026 editions. Remember this is a ranking by size of AUM, not necessarily firm quality or returns.