





Goldman Sachs advised on $1.53 trillion of M&A through September 2026, a 44.3% market share, after leading the full-year 2025 table with $1.66 trillion. The most active M&A investment banks by deal value are Goldman Sachs, JPMorgan and Morgan Stanley, the only advisors above $1 trillion in both periods; by deal count the leaders are PwC and Houlihan Lokey. I spent over a decade as an M&A advisor before founding DealRoom in 2012, and that gap between value and count is the first thing to check before picking an advisor. Below: the most active M&A advisors ranked on 2025 data, a 2026 update and fees by deal size.
The short version (2025 full year):
- Most active by deal value: Goldman Sachs. $1.66 trillion advised, 36.4% of a $5.1 trillion market.
- Most active by deal count: PwC. 660 deals, ahead of every investment bank on volume.
- Most active investment bank by deal count (Global Data): Houlihan Lokey, 318 mandates. On Merger market's count PwC led with 660 and Goldman Sachs had 515.
- Fastest riser in 2025: Wells Fargo. Up 61.7% year over year and into the global top 10, though it slipped to 11th in Merger market's 9M 2026 table.
2026 so far (through September 30): Goldman Sachs $1.53 trillion and a 44.3%share; PwC 451 deals (Mergermarket). - Best fit for a mid-market sell-side: Houlihan Lokey, Rothschild & Co or a Big Four team.
- Best fit for a cross-border deal: Citi or Lazard.
- Best fit for a board-level strategic mandate with no financing conflict: Centerview Partners or Evercore.
How We Evaluated
We ranked advisors on four dimensions: total announced deal value, number of announced mandates, disclosed advisory fee revenue and regional or sector leadership. Inputs are full-year 2025 league tables from Merger market via ION Analytics, the Global Data Financial Deals Database, LSEG data reported by Finimize and each public firm's own Q4 2025 results, plus Merger market's 9M 2026 rankings and LSEG's Q3 2026 data as reported by Reuters for the 2026 year-to-date section. Tier classifications (bulge bracket, elite boutique, middle market, regional leader) are DealRoom editorial characterizations, not provider data. No figure on this page is estimated. Last reviewed October 2026, with a 2026 year-to-date update through September 30; the ranked list refreshes when full-year league tables publish each January.
Transparency note. DealRoom publishes this guide and sells M&A lifecycle software. We do not compete with any advisor listed and we take no fee from any of them. We link to the primary league tables so you can check every number yourself.
The most active M&A advisors by 2025 deal value
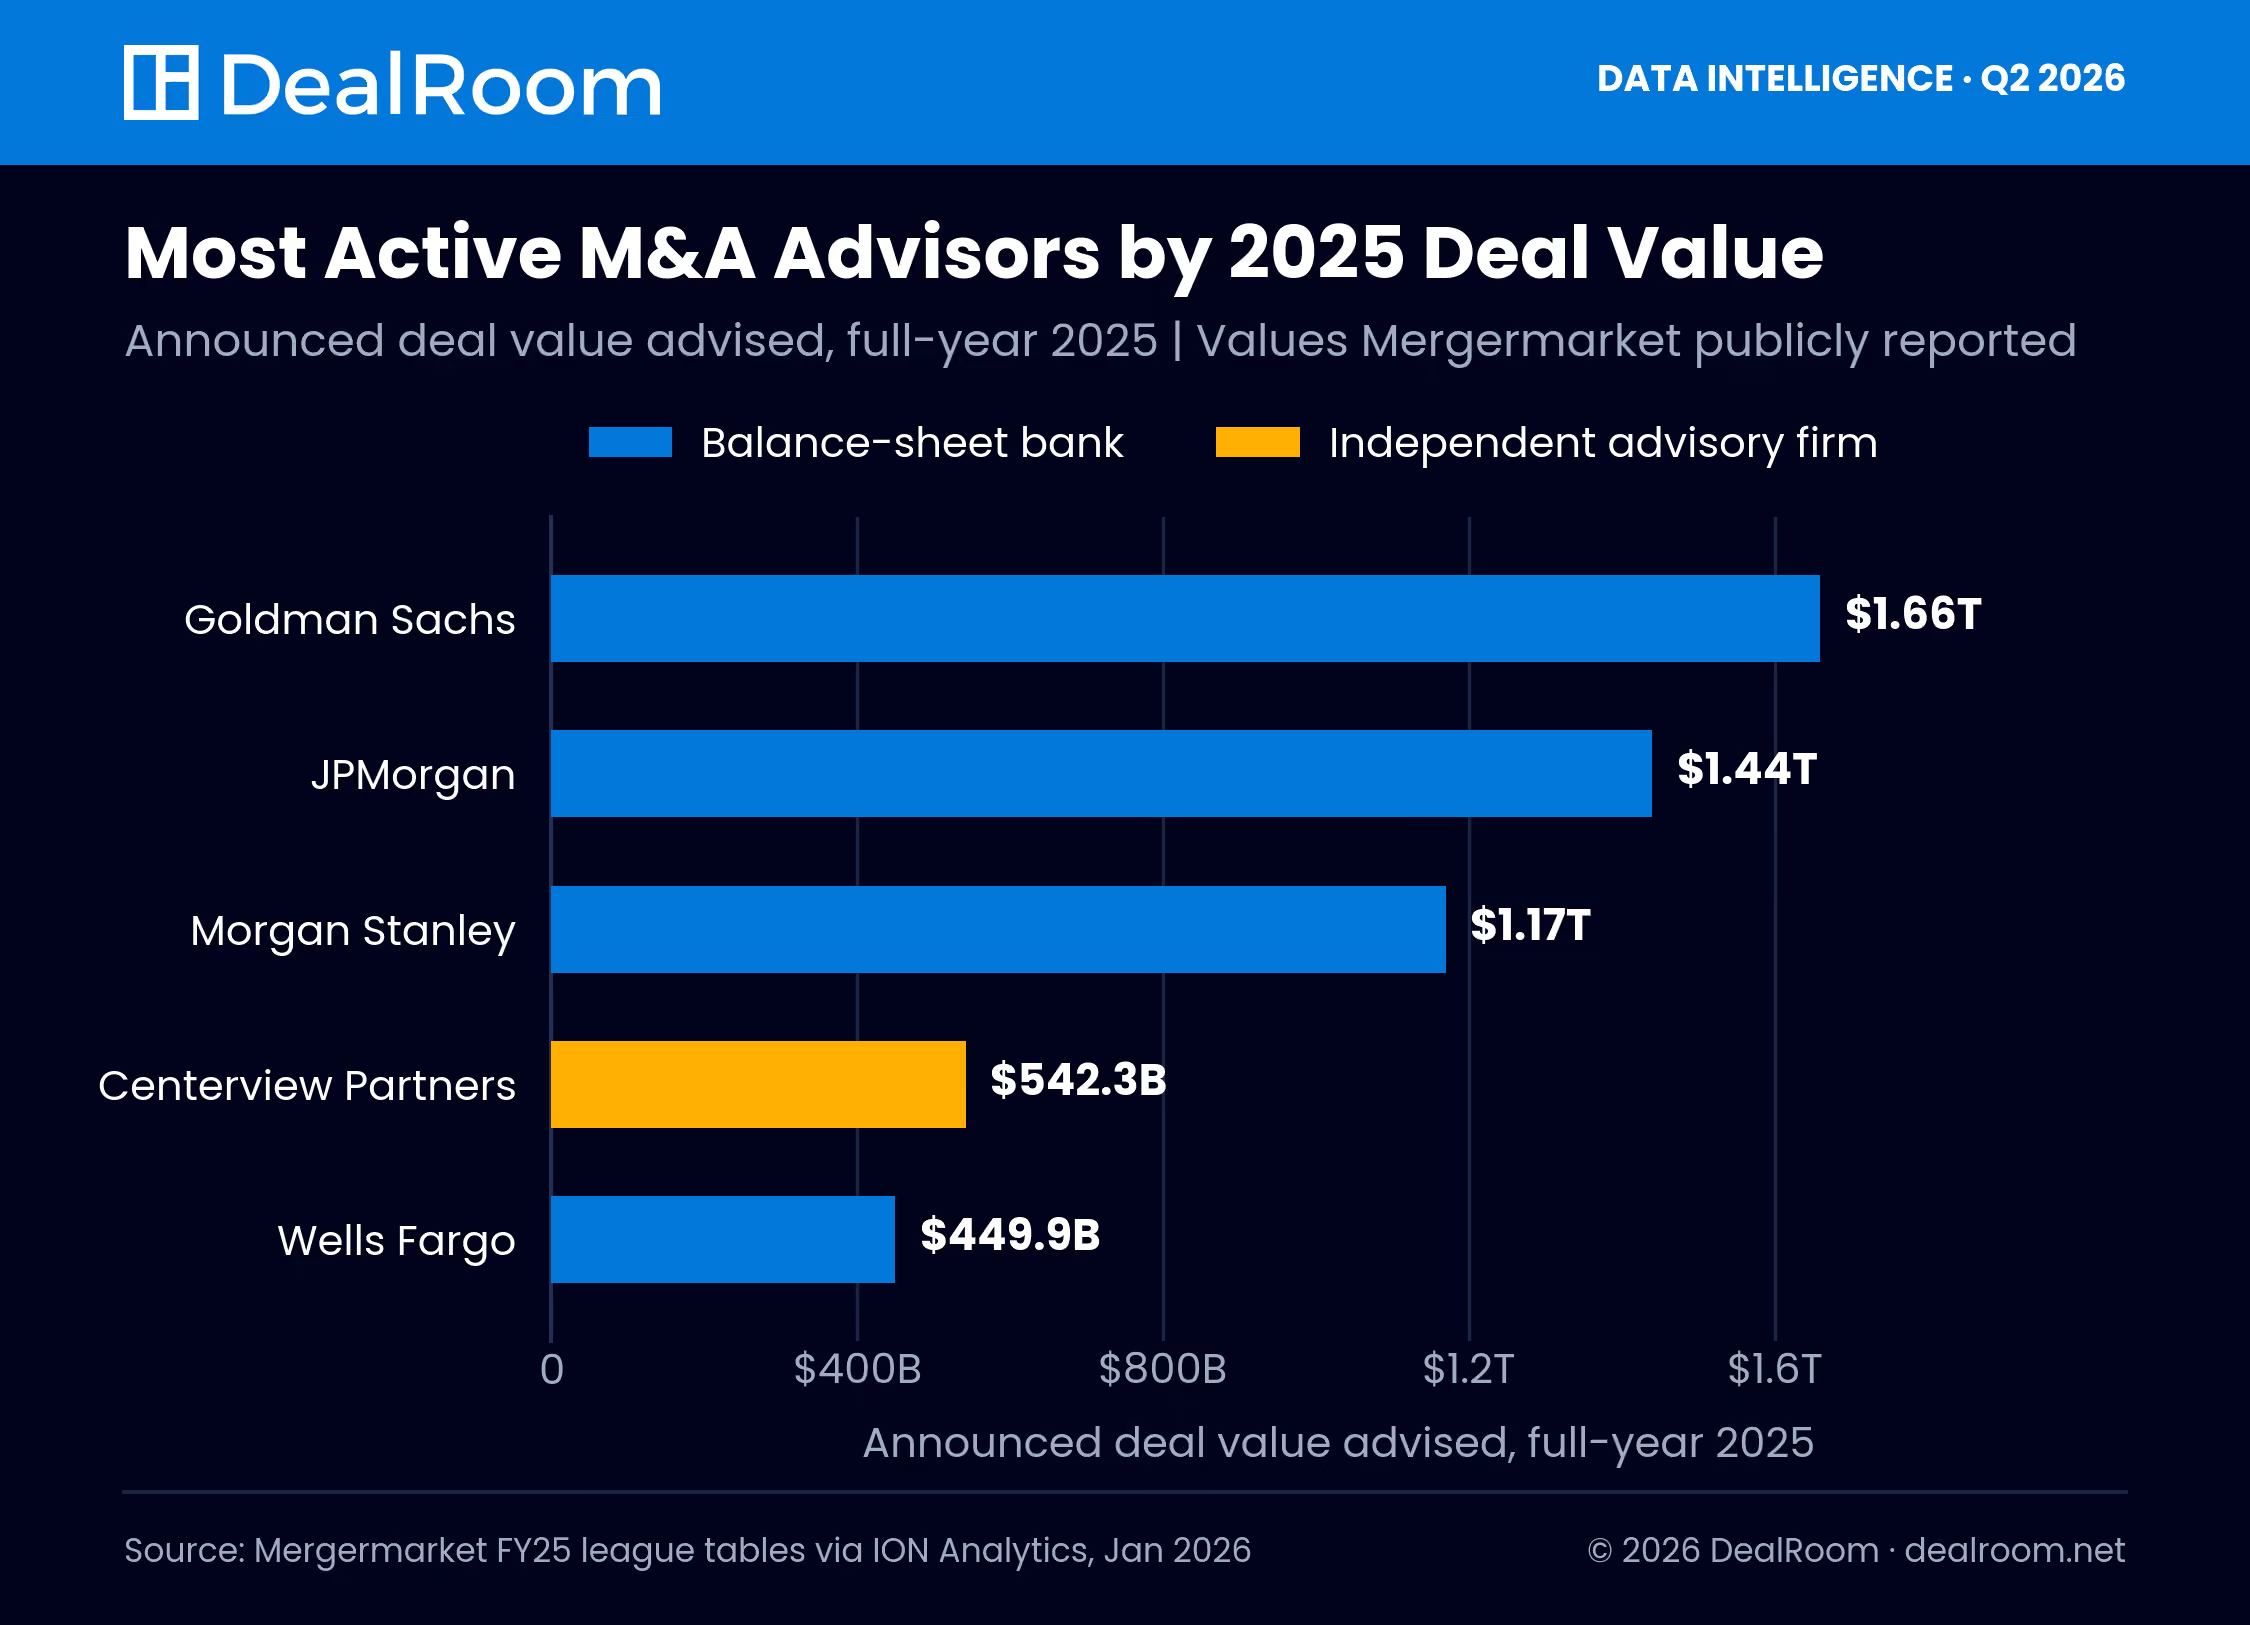
Goldman Sachs tops Mergermarket's full-year 2025 league tables with $1.66 trillion in announced deal value, equating to 36.4% of a market which Mergermarket values at $5.1 trillion. JPMorgan and Morgan Stanley round out the top three. All three advisors have advised on over $1 trillion worth of deals. Centerview Partners and Wells Fargo moved into the global top 10, replacing UBS (11th) and Deutsche Bank (13th).
The numbers look a little different from LSEG’s version of the same table, which tells the same story from a different angle. Goldman advised on $1.48 trillion of the 2025 deal value, or about 32% of the total. The firm also earned an estimated $4.6 billion in M&A fees, more than any other bank. LSEG’s league table counted 68 deals worth $10 billion or more valued at roughly $1.5 trillion combined. That’s more than double from 2024 and the most in LSEG’s history dating back to 1980. Goldman advised on 38 of those deals.
The companies leading the marquee mandates illustrate where value was parked. Goldman ran the sell side of the $56.6 billion Electronic Arts buyout, the largest leveraged buyout ever, which closed in August 2026 at $210 a share. JPMorgan advised Warner Bros Discovery through the contest between Netflix and Paramount Skydance; Paramount's $31-a-share, roughly $110 billion acquisition closed on October 6, 2026 after Netflix withdrew in February. Morgan Stanley sat on the buy side of UnionPacific's $85 billion Norfolk Southern acquisition, which the Surface Transportation Board is reviewing on a schedule that runs into 2027. JPMorgan and PJT Partners advised Kimberly-Clarkon its $48.7 billion acquisition of Kenvue, expected to close in the fourth quarter of 2026. Transactions of this magnitude dwarf entire mid-market sectors. Check out our running list of the largest M&A deals here.
The 10 Most Active M&A Advisors
1. Goldman Sachs
Tier: Bulge bracket · 2025 advised value: $1.66 trillion · Megadeals: 40 · Market share: 36.4%
Best for: the largest and most contested sell-sides.
Goldman led the Merger market global table by a margin no other bank came close to, advising on more than a third of all announced value. Roughly 60% of its 2025 mandates were sell-side. It ran the sell-side on the $56.6 billion Electronic Arts buyout, the largest leveraged buyout on record, which closed in August 2026. Through September 2026 it leads again with $1.53 trillion advised and a 44.3% share.
Where it is not the answer: a $40 million sell-side will not get a senior Goldman team. It probably will not get an engagement letter.
2. JPMorgan
Tier: Bulge bracket · 2025 advised value: $1.44 trillion · Megadeals: 32 · Growth: up 44.2%
Best for: deals where advisory and acquisition financing come from the same house.
JPMorgan posted the largest year-over-year jump of any top-three bank. It advised Warner Bros Discovery on the sell-side of the roughly $100 billion contest between Netflix and Paramount Skydance.
Where it is not the answer: if you want an adviser with no lending relationship on the other side of the table, an advisory-only boutique removes the question.
3. Morgan Stanley
Tier: Bulge bracket · 2025 advised value: $1.17 trillion · Megadeals: 24 · Mandates: 295
Best for: large-cap buy-side work in tech, media, industrials and consumer.
Morgan Stanley is the clearest example of why the two metrics disagree. It ranks third by Mergermarket value and second by GlobalData deal count, on $872.7 billion by GlobalData's value measure. It ran buy-side for Union Pacific on the $85 billion Norfolk Southern acquisition and for Kimberly-Clark on its $51.4 billion Kenvue acquisition.
Where it is not the answer: mid-market processes below roughly $500 million.
4. Centerview Partners
Tier: Elite boutique · 2025 advised value: $542.3 billion · Growth: up 52.3%
Best for: board-level strategic advice with no financing conflict.
Centerview broke into the global top 10 for the first time, displacing UBS and Deutsche Bank alongside Wells Fargo. It has no underwriting or lending arm, so its advice carries no balance-sheet interest.
Where it is not the answer: if you need committed financing alongside the advice.
5. Evercore
Tier: Elite boutique · 2025 advisory fees: $3.3 billion, up 34% · Announced value: $514 billion
Best for: large-cap advisory and restructuring where fee transparency matters.
Evercore reported record full-year M&A and IPO advisory fees of $3.3 billion, third globally in advisory revenue among public firms. It is one of the few advisors whose fee take is disclosed rather than inferred.
Where it is not the answer: cross-border deals needing a large on-the-ground network.
6. Bank of America
Tier: Bulge bracket · 2025 advised value: $485.8 billion · Rank: top 5 by value
Best for: industrials and consumer M&A that needs acquisition financing.
Fifth by GlobalData value and fifth in APAC excluding Japan by Mergermarket volume.
Where it is not the answer: deals where a lending relationship creates a conflict.
7. Wells Fargo
Tier: Bulge bracket · 2025 advised value: $449.9 billion · Growth: up 61.7%
Best for: US corporate M&A from a bank building its advisory franchise.
The fastest riser in the 2025 tables. Wells Fargo grew advised value 61.7% and entered the global top 10 for the first time.
Where it is not the answer: complex cross-border work, where the franchise is still young.
8. Houlihan Lokey
Tier: Middle market · 2025 mandates: 318 · Rank: No. 1 globally by deal count
Best for: mid-market sell-sides and private equity processes.
The only advisor above 300 announced mandates and number one by deal count for both private equity buyouts (68) and exits (95). If your deal is under $1 billion, this is the bank that does the most of them.
Where it is not the answer: a $10 billion-plus strategic megadeal.
9. Lazard
Tier: Elite boutique · 2025 advisory revenue: $1.83 billion adjusted, up 5%
Best for: cross-border M&A and sovereign or restructuring mandates.
Lazard posted record adjusted financial advisory revenue of $1.83 billion. Its global head of M&A flagged rising multiples paid by buyers through 2025.
Where it is not the answer: domestic mid-market processes where the fee will not justify the team.
10. Rothschild & Co
Tier: Middle market · 2025 mandates: 171 · Rank: top 5 globally by deal count
Best for: European and cross-border deals at any size.
Rothschild ran a high-volume year across the size range, with particularly deep European coverage.
Where it is not the answer: US-only processes, where domestic banks have denser coverage.
Also ranked: Citi ($2.0 billion in 2025 M&A fees, top advisor in India at $26.7 billion), Moelis & Company, Nomura (No. 1 in Japan at $143.6 billion), RBC Capital Markets (No. 1 in Canada at $113.3 billion across 55 deals), PwC (660 deals, No. 1 globally by count), KPMG (525 deals) and Deloitte (478 deals). All 16 are in the comparison table below.
Why League Tables Disagree
Mergermarket, LSEG, Dealogic and GlobalData each have proprietary guidelines around eligibility of deals, attribution of multiple advisors and when deal value counts (announcement value vs. closing value). That's why you'll see Goldman worth $1.66 trillion on one leaderboard and $690.2 billion on another for the same year. Approach league tables as bankers would: useful for directional trends, but not an audited fact. The firms that appear across all four providers are the ones to take notice of.
Reconciling the Goldman megadeal counts. This page cites Goldman at 40 megadeals on the Mergermarket basis and 38 of the 68 deals above $10 billion on the LSEG basis. Both are correct. The providers use different deal-value thresholds, different inclusion rules for withdrawn transactions and different credit rules for multi-advisor mandates.
2026 year to date: the league table through September
Goldman Sachs, JPMorgan and Morgan Stanley lead the M&A league table for 2026 year to date, in the same order as 2025, but the rest of the top 10 has changed. Through the first nine months of 2026 Mergermarket counts $4.4 trillion of global M&A, up 27% year on year, with 60 megadeals above $10 billion making up a record 35% of volume. LSEG counts $3.9 trillion, up 28%, and puts the third quarter at $993 billion, down 41% from the second quarter and the first quarter below $1 trillion since Q2 2025.
By deal count, PwC still leads with 451 deals, Houlihan Lokeyis second with 359, Goldman Sachs third, JPMorgan fourth with 355 and Morgan Stanley fifth with 299. What changed since 2025: Lazard, UBS and Rothschild moved into the top 10 by value and Wells Fargo, Barclays and Jefferies dropped out. On LSEG's table Morgan Stanley moved ahead of JP Morgan into second, with BofA Securities and Citi completing the top five. Goldman's advisory revenue for the nine months was $4.53 billion, up 34% on the same period of2025. Mergermarket's 9M 2026 release does not name the advisors in positions 4,5, 7 and 10, so the ranked list on this page stays on full-year 2025 data until the 2026 tables publish in January 2027.
What to look for when you hire an advisor
League table position tells you how busy a bank was. It does not tell you whether it is right for your deal. Five things do.
Deal size fit. A bank's league table position is built from deals far larger than most. The mid-market sweet spot is roughly $50 million to $1 billion; below about $15 million, a quality banker's fee cannot be supported by the transaction.
Sell-side or buy-side bias. Roughly 60% of Goldman's 2025 mandates were sell-side. A bank that mostly sells will run a different process than one that mostly buys.
Financing conflict. Bulge brackets underwrite and lend. Elite boutiques do not. If your counterparty's lender is also your adviser's employer, decide upfront whether that matters to you.
Sector and geography coverage. Nomura leads Japan. RBC leads Canada. Citi leads India. National champions beat global brands inside their own market more often than the global table suggests.
Who actually staffs it. The named partner who pitches is not always the person who runs the process. Ask which team. Ask for their last three comparable deals by size and sector.
Bulge bracket, elite boutique or middle market: what each is like across the table
Bulge bracket banks
Goldman Sachs, JPMorgan, Morgan Stanley, Bank of America, Citi and now Wells Fargo all combine advisory with a balance sheet. They can advise the deal, finance it and hedge it all in one engagement. That's why they win most megadeal mandates. If you’re facing one as a counterparty, you’re up against a deep bench, standardized process discipline and a team that is likely running ten other live deals. Expect polish. Do not expect the senior banker who pitched the deal to be at every working session.
Elite boutiques
Centerview, Evercore, Lazard, Moelis and PJT don't do lending. They don't do underwriting. They sell advice only. There are fewer conflicts to navigate. Evercore had record M&A and IPO advisory fees of $3.3 billion in 2025, a 34% jump year-over-year. Evercore ranked third globally among public companies for advisory revenues. Rival Lazard reported record adjusted financial advisory revenue of $1.83 billion. Centerview climbed into the top 10 globally last year on 52.3% volume growth. Across the street, when you get a boutique mandate, the named senior partner is typically working the deal. The bench is thinner so work can take longer if the firm is stretched.
Middle-market specialists
Houlihan Lokey, Rothschild, Jefferies, Lincoln, Baird, William Blair and the Big Four deal teams thrive in the $50 million to $1 billion range where most deals occur. Houlihan Lokey advised on 318 mandates, which made it the most active advisor globally by volume. Mergermarket ranked Houlihan Lokey number one by deal count for both private equity buyouts (68) and private equity exits (95). As a corporate buyer transacting with a PE fund in 2026, there is a non-zero chance Houlihan Lokey is running your process. These firms have tighter, more standardized processes than their megadeal brethren. The data room will open quicker and the timeline letter can prove it.
How M&A advisory fees actually work
Fee structures are negotiated on a deal-by-deal basis, but the framework remains the same: a work fee (retainer) and a success fee paid at closing. The latest available public survey is The Firmex and Axial M&A Fee Guide, which surveyed mid-market advisors. The most frequent package consists of a one-time work fee of over $15,000 applied towards a success fee that decreases with larger deal values.
Source: Firmex and Axial M&A Fee Guide, survey of mid-market M&A advisors. The same guide notes many advisors still quote the Lehman formula or a variant: a descending percentage scale (for example 5% of the first million, 4% of the second) as deal size rises.
Percentages compress above the mid-market. Megadeal advisory fees are negotiated and frequently come in well below 1% of deal value. Consider the 20/25 tallies: Goldman's roughly $4.6 billion in M&A fees were earned on $1.48 trillion of value advised on LSEG's calculations, or an effective rate of approximately 0.3%. Sell-side fees are also higher than buy-side fees for an equivalent deal size due to the fact that the bank leads the process.
When to hire a bank and when to run it in-house
We write software for internal deal teams, so we observe this decision being made every week. The truth is it depends on where you sit in the deal and how frequently you transact. In our State of M&A report, we characterized the current cycle as “transact to transform,” meaning companies are buying the capabilities they can’t build quickly enough. Teams doing that type of programmatic M&A typically run corporate development internally and hire banks selectively.
Hire a bank when:
- You want to sell. A banker-run auction creates competitive tension a solo seller can't manufacture, and the fee usually pays for itself in price. This is the strongest case for a mandate.
- The deal will involve financing or require a fairness opinion. Most balance-sheet banks bundle both. Boards with shareholder litigation risk want the opinion regardless.
- Transaction volume is low. A team doing one deal every three years should rent process expertise instead of building it.
Run it in-house when:
- You are a programmatic acquirer and have an existing pipeline. Repeat buyers understand their targets, their multiples and their integration costs far better than any banker putting a CIM in front of them.
- The target is proprietary. If you found the deal and exclusivity is genuine, a sell-side bank coming in to help only competes with you.
- Deal size is below banker economics. Minimum success fees mean a $15 million deal often cannot support a quality banker. Corp dev and outside counsel will do.
We wrote about this trend in our State of M&A report. We highlighted that approximately $1.1 trillion of the $4 trillion of private equity dry powder was deployed in buyout funds against the clock. That money arrived in 2025: buyouts totaled $1.1 trillion, Reuters reported, an increase of 51 percent from the prior year. More PE activity equals more banker-driven processes. Deal-minded buyers who curate their own deal pipeline enter these processes ahead of the curve and are armed with better information than buyers who begin at the teaser.
The banker-run sell-side process from the buyer's seat
If a Houlihan Lokey or Jefferies is running the sale, the process itself will be the product. Knowing the choreography keeps you from being played by it. Here is the typical process:
- Teaser and NDA. You receive a one-page anonymous company profile. Execution of the NDA provides access to the CIM. You are added to a buyers list that the banker ranks by strategic fit and financial capacity to close.
- Process letter and IOI. The banker schedules a non-binding indications of interest (IOI) date. Opening bids will typically anchor to the CIM adjusted EBITDA. Bid the range the data supports, not the range implied by the process letter.
- Management meetings and data room. A curated group of bidders move forward. The data room opens up in phases. Every question you ask in the data room reveals your thesis to the sell side. Be strategic about the order in which you request information.
- LOI and exclusivity. Execution of final bids with markup of purchase agreement. The banker’s role during exclusivity is maintaining the credibility of the second bidder until the deal signs.
There are two real-world countermeasures. Number one: Operate on your own schedule: A well-oiled buy-side M&A process with pre-developed diligence request lists will prevent your process from being pushed by the banker's timeline (and risk thresholds). Number two: View the CIM as an advocacy document, not a disclosure document. Our due diligence guide discusses the request list that helps you bridge from the banker's numbers to reality. For a broader discussion of the advisor universe, check out our M&A advisory guide on how mandates are scoped and executed.
Working at these banks
Compensation, hours and culture vary far more by team and by year than by tier, and none of the league table data on this page measures any of them. Broadly: bulge brackets offer the most deal flow and the longest hours, elite boutiques pay juniors the most on the smallest teams and middle-market firms give earlier client contact on more manageable hours.
Frequently asked questions
Who are the top investment banks by M&A activity?
The top investment banks by M&A activity in 2025 were Goldman Sachs, JPMorgan and Morgan Stanley, which advised on $1.66 trillion, $1.44 trillion and $1.17trillion of announced deals according to Mergermarket. Goldman's total was a36.4% share of the market. By number of deals the answer depends on the provider: Mergermarket credits PwC with 660 deals and Goldman Sachs with 515,while Global Data ranks Houlihan Lokey first among investment banks with 318mandates. Through September 2026 Goldman Sachs still leads on value with $1.53trillion.
Which investment bank should I hire to sell my company?
Hire the investment bank that does the most deals of your size, not the biggest name. Below roughly $100 million, a middle-market specialist such as Houlihan Lokeyor a Big Four corporate finance team will put a senior banker on your sale; Houlihan Lokey advised on 318 mandates in 2025, more than any other investment bank by Global Data's count. Between $100 million and $1 billion, Rothschild& Co, Jefferies and the elite boutiques compete hardest. Above $1 billion, Goldman Sachs, JPMorgan and Morgan Stanley advised on most of 2025's announced value.
Who were the advisors on the largest M&A transactions of 2025?
Goldman Sachs, JPMorgan and Morgan Stanley advised on the largest M&A transactions of 2025. Goldman Sachs ran the sell side of the $56.6 billion Electronic Arts buyout, the largest leveraged buyout on record (closed August 2026). JP Morganadvised Warner Bros Discovery through the Netflix and Paramount Skydance contest; Paramount's roughly $110 billion acquisition closed on October 6, 2026.Morgan Stanley advised Union Pacific on its $85 billion Norfolk Southern acquisition, now in Surface Transportation Board review. JPMorgan and PJT Partners advised Kimberly-Clark on its $48.7 billion acquisition of Kenvue, expected to close in Q4 2026.
How are fees paid for M&A advisory work?
M&A advisory fees are paid in two parts: a work fee (retainer) during the engagement and a success fee at closing. In Firmex's 2024-25 Global M&A Fee Guide, a survey of 456 middle-market advisors, the average success fee was 4.8%on a $5 million deal, 2.7% at $50 million and 1.9% at $150 million. The most common work fee was $5,000 to $10,000, charged monthly or as a one-time fee and usually credited against the success fee. Megadeal fees are negotiated and typically run well under 1% of deal value.
What distinguishes a bulge bracket bank from an elite boutique?
The difference between a bulge bracket bank and an elite boutique is the balance sheet. A bulge bracket bank such as Goldman Sachs or JPMorgan pairs M&A advice with lending, underwriting and hedging, so it can advise and finance the same deal. An elite boutique such as Centerview, Evercore or Lazard sells advice only, with no lending or underwriting arm, so it carries fewer financing conflicts and the senior partner who pitches usually works the deal. In 2025Evercore earned $3.3 billion in advisory fees, third among public firms, without any balance-sheet business.
Should I have an investment bank to buy or sell a company?
If you are selling a company, you should usually have an investment bank: a banker-run auction creates competitive tension that typically lifts the price by more than the fee, which averages 4.8% on a $5 million deal and 1.9% at $150 million in Firmex's 2024-25 survey. If you are buying, you need one less often: a corporate development team with its own pipeline can run a proprietary deal without an advisor, and below roughly $15 million the deal often cannot support a banker's minimum fee. Buyers hire a bank when the deal needs acquisition financing or a fairness opinion.
What is an M&A league table?
An M&A league table lists investment banks by value or number of announced deals for a certain period of time. The league tables are published by data providers like Mergermarket, LSEG, Dealogic and GlobalData. Each league table has unique qualification and deal crediting criteria so rankings will differ between providers for the same year.